Available for a 6-month final-year internship, starting January 2027

I connect actuarial calculation with artificial intelligence, and I check every number.

Data science engineering student at ESPRIT and MSc Actuarial Science student at Le Mans Université. I build IFRS 17, reserving and pricing tools where code does the calculation and the language model does the explaining.

5,000 mortality scenarios, simulated just now in your browser

Each line is one possible path of a mortality index over 25 years: a random walk with drift, the engine of the Lee-Carter model I use to measure longevity risk. Illustrative parameters.

  • Simulated paths
  • Median
  • 90% of scenarios

Projects

Three studies that each answer one precise question, then the platforms and tools. Every figure comes from the repository that computes it.

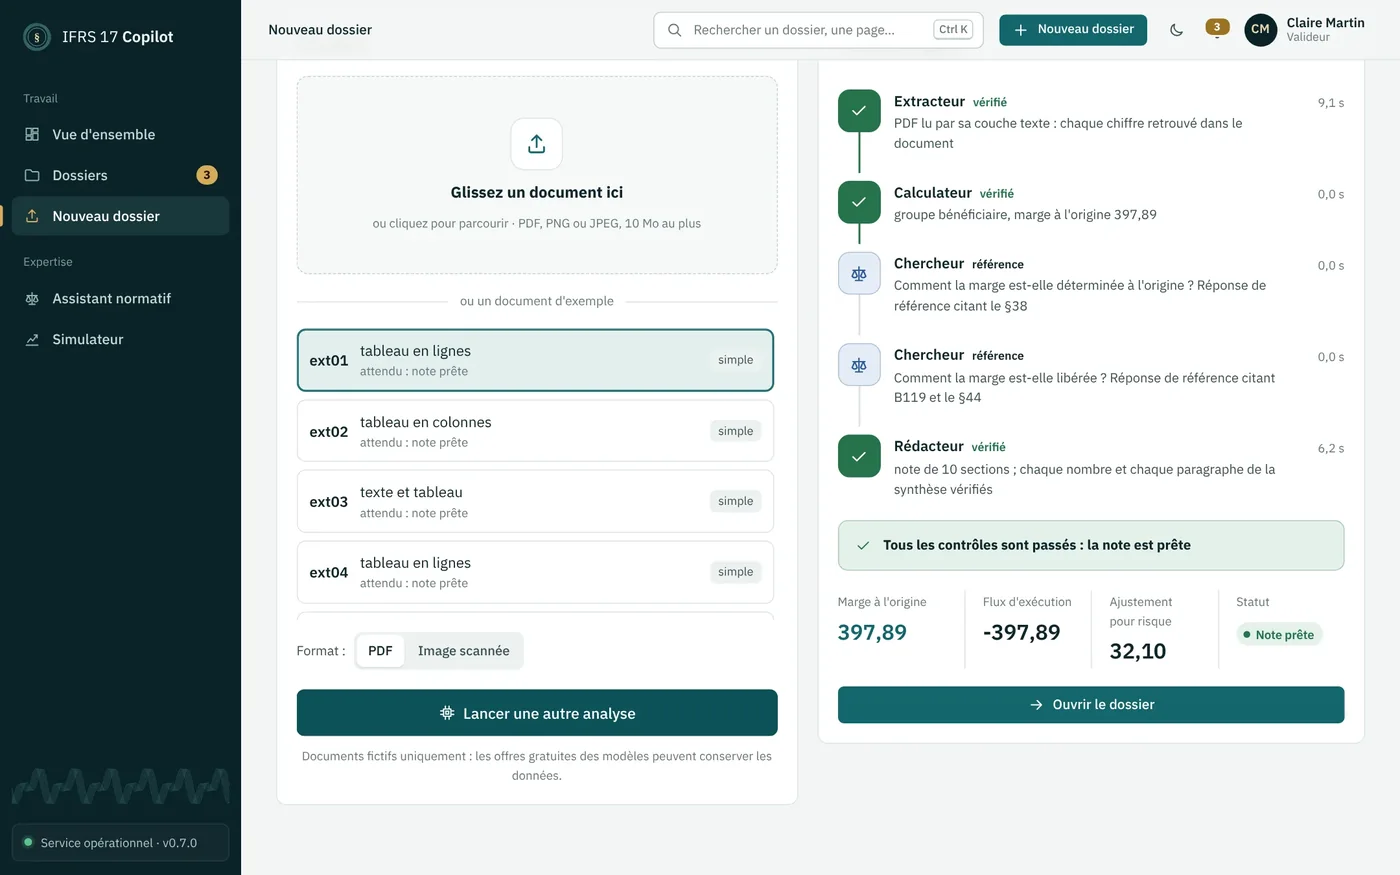
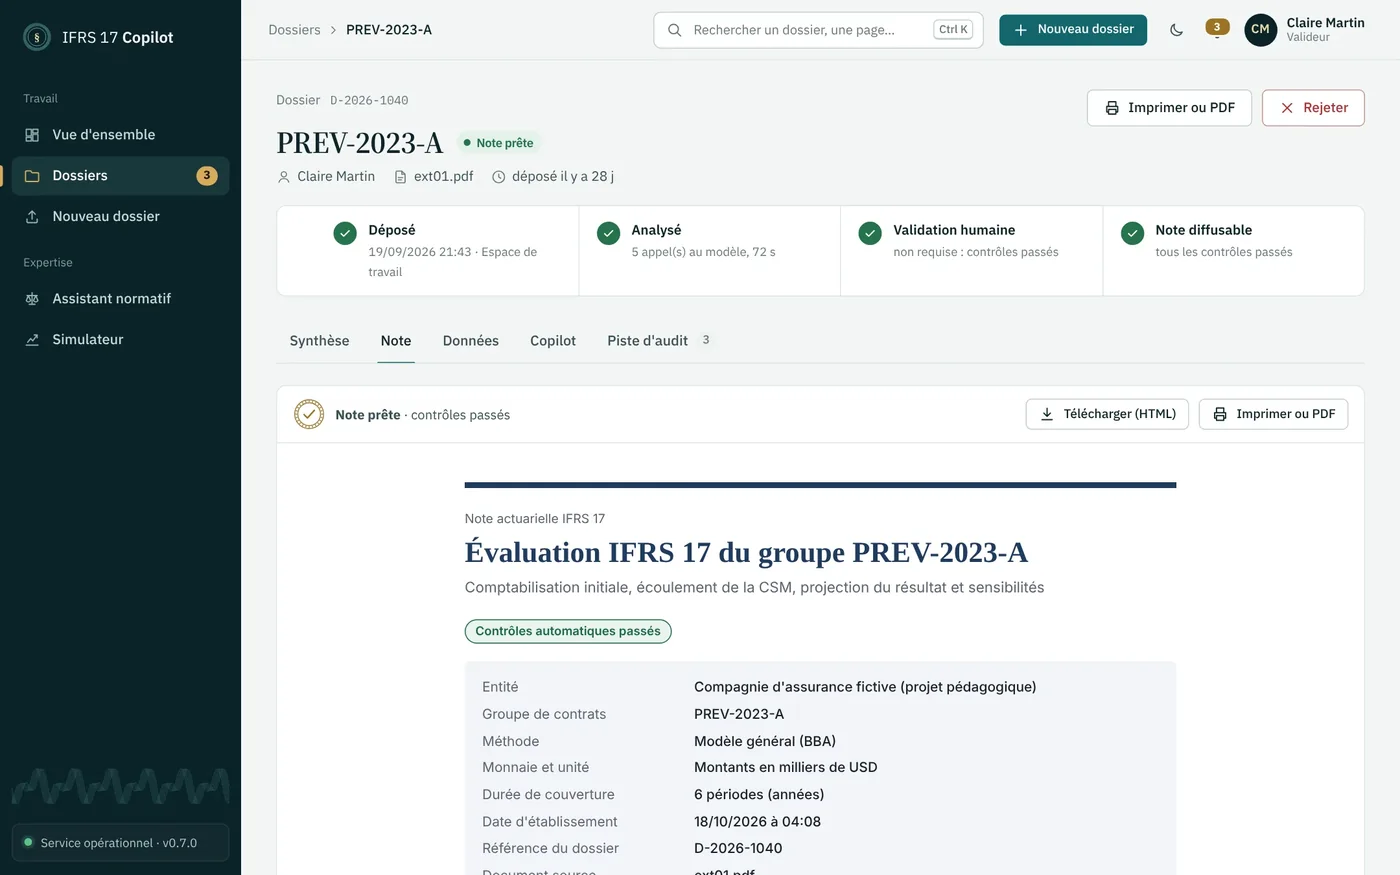
Can a language model write an IFRS 17 memo without making up a number?

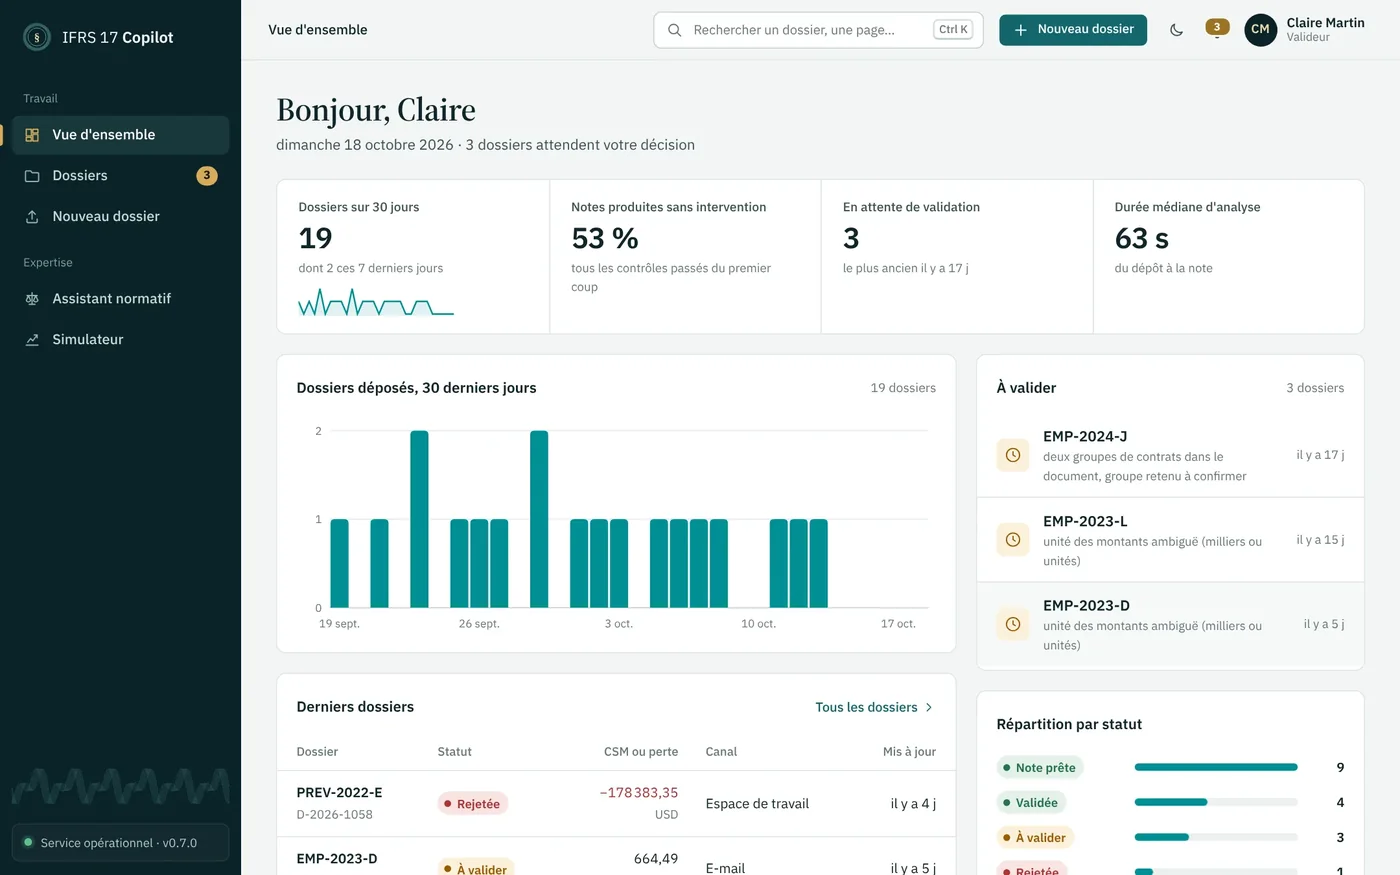
IFRS 17 Copilot

A multi-agent copilot reads an insurance file (PDF, scan, Excel or a spoken question), computes the contractual service margin and the liability for incurred claims, then writes a memo that is cited, checked and submitted for human approval. Code calculates, the model explains.

Recomputed by an independent R script
50 / 50 files to the cent
Retrieval in the standard
Recall@5 from 0.52 to 0.75
Automated tests
370+, CI passing

Python, FastAPI, LangGraph, RAG, Qdrant, n8n
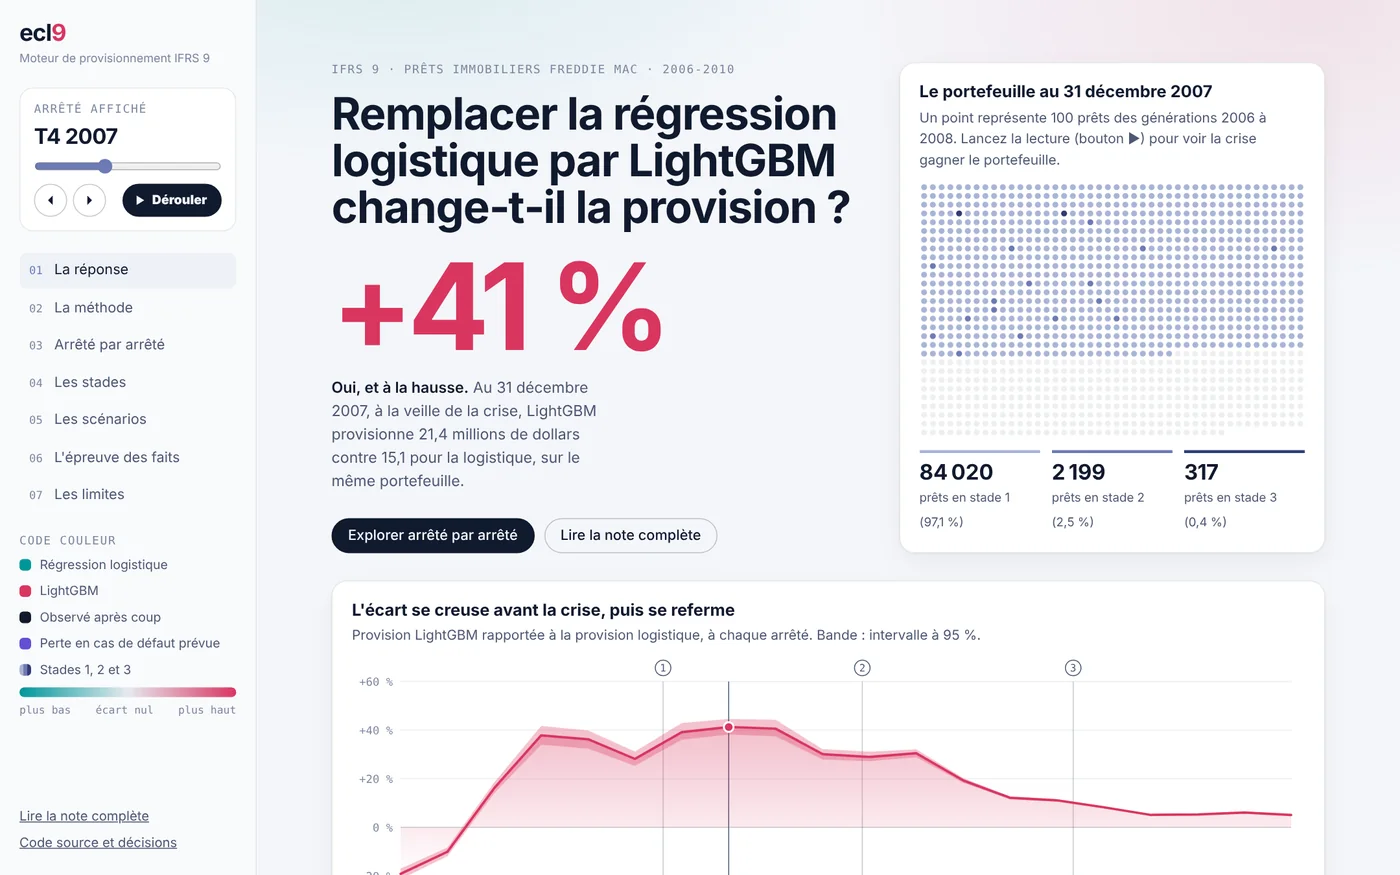
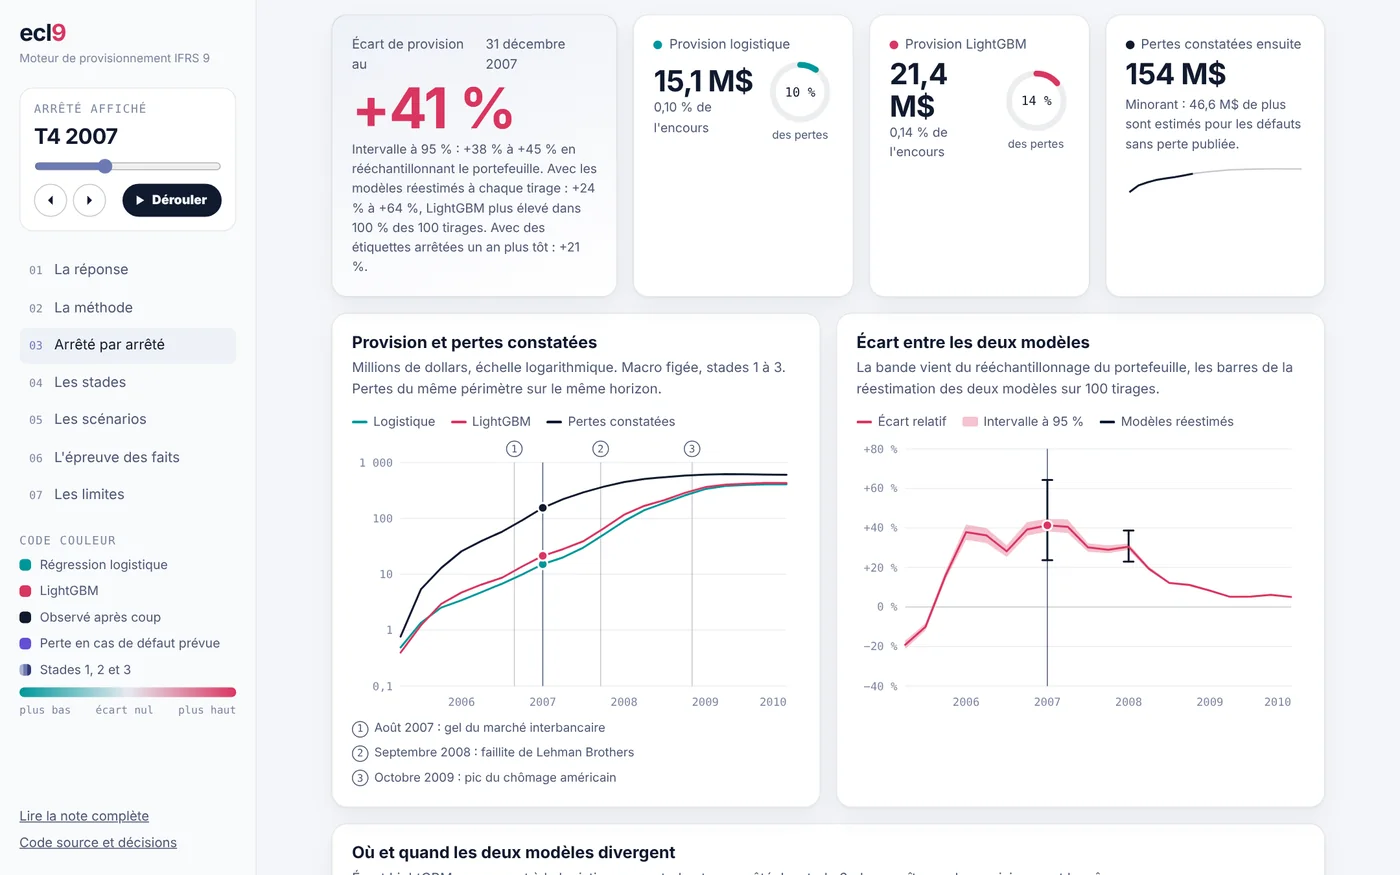
Does machine learning really change the IFRS 9 allowance?

ecl9

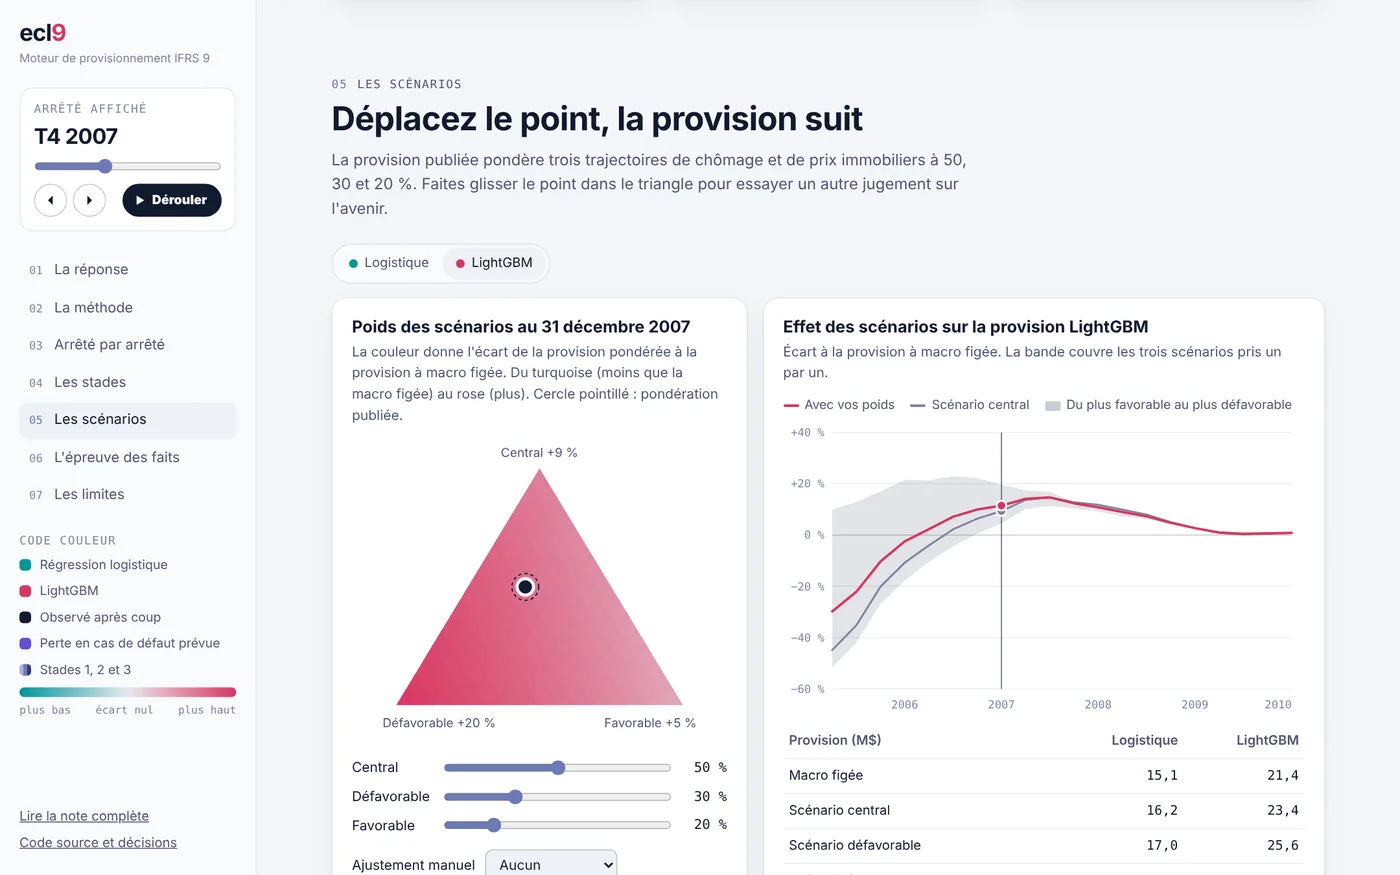
A loan-by-loan expected credit loss engine on Freddie Mac US mortgages. The models are trained on 2000-2005 and tested on 2006-2008: they go through the crisis without having seen it.

LightGBM versus logistic, end of 2007
+49% allowance
Share of later realised losses covered
only 9 to 13%
Independent recalculation in R
50 loans

Python, LightGBM, discrete-time survival, pytest, Quarto

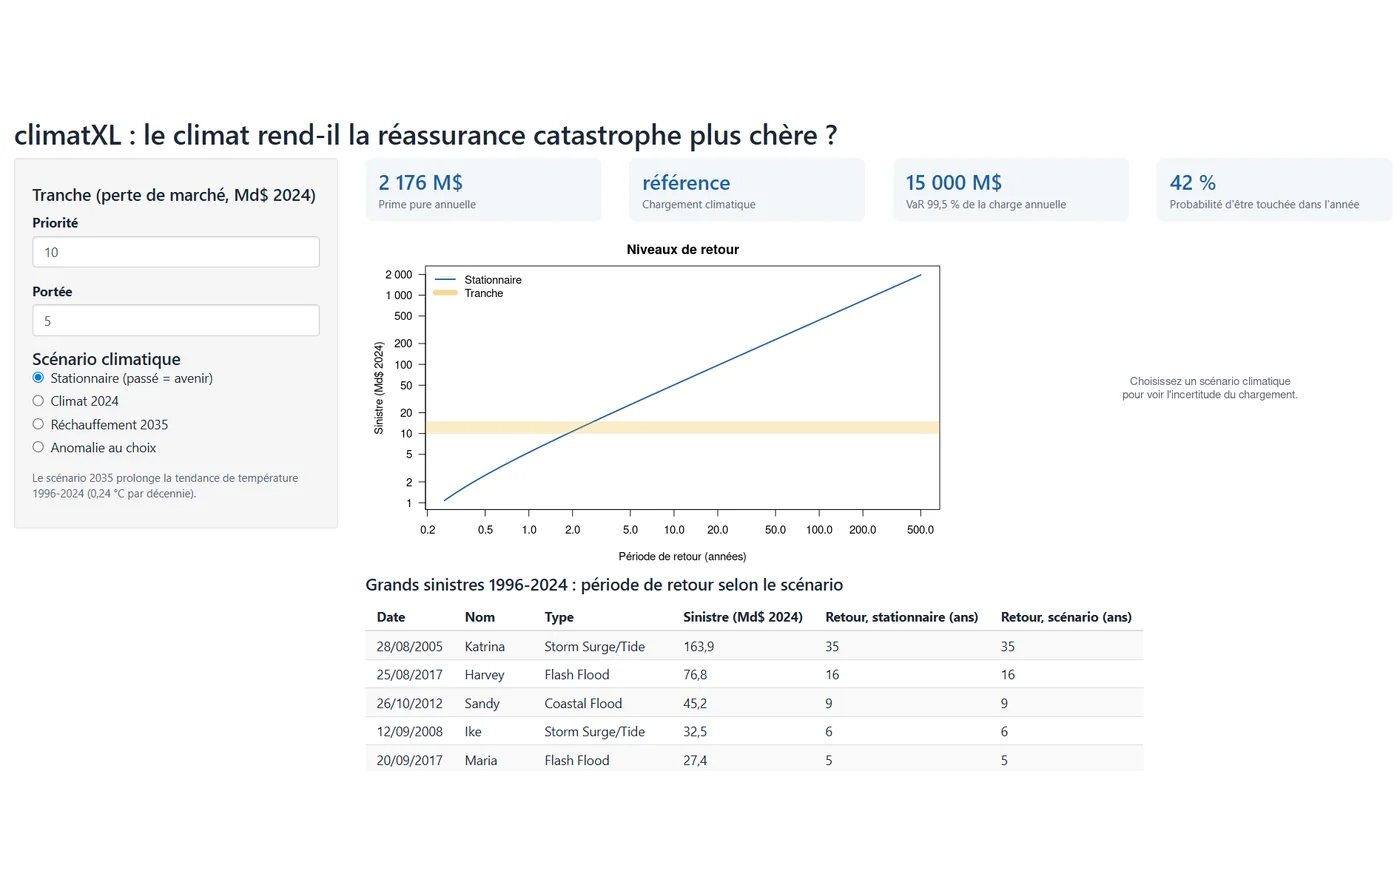
Does climate make catastrophe reinsurance more expensive?

climatXL

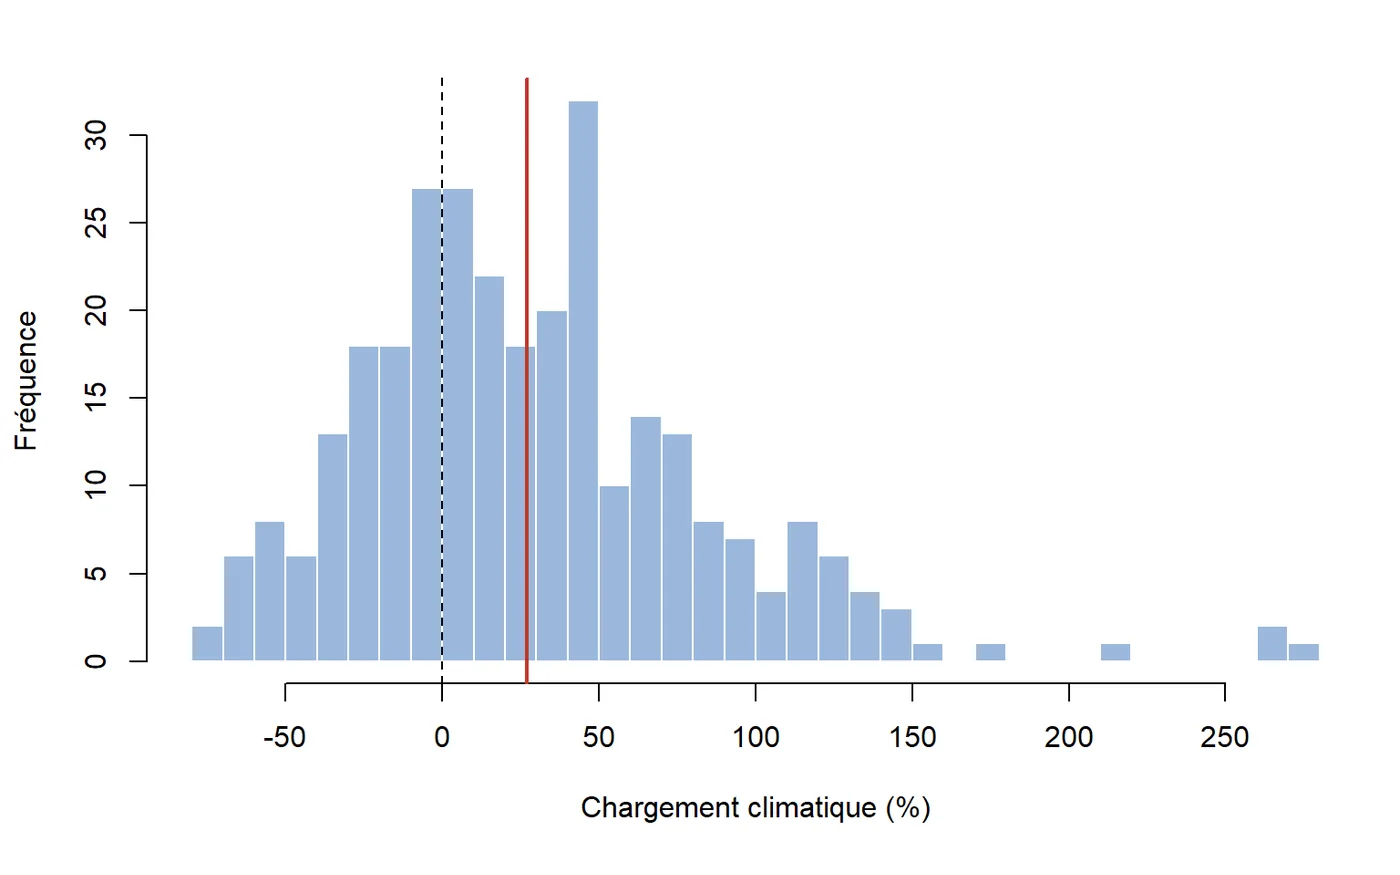
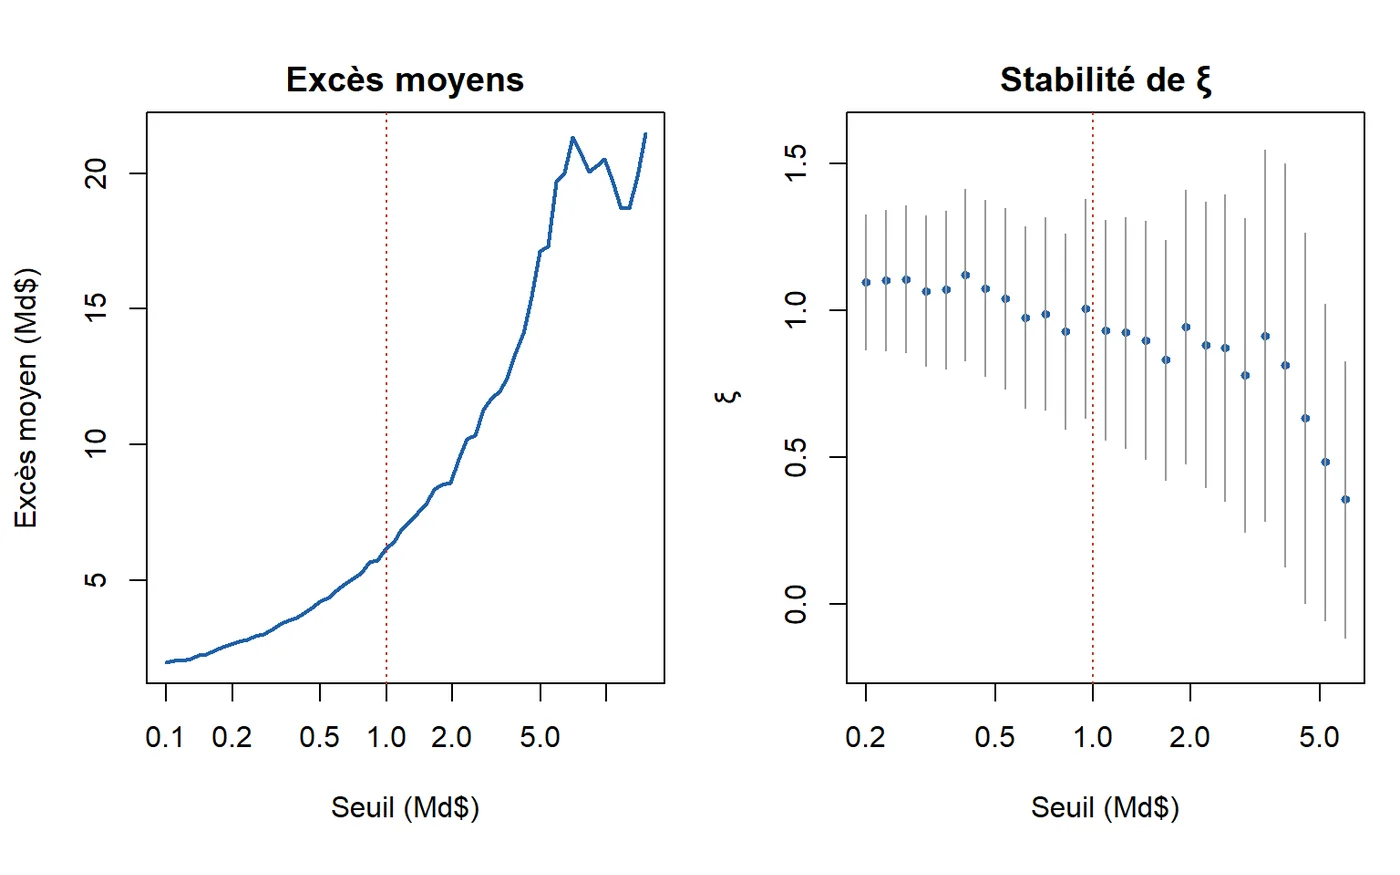
An R package that fits extreme value distributions, first stationary and then climate-dependent, to NOAA damages for 1996-2024, and derives the premium of an excess-of-loss layer. The answer over this period: not demonstrably.

Pure premium of the layer, 2024 then 2035
$2,176m to $2,762m
Validation
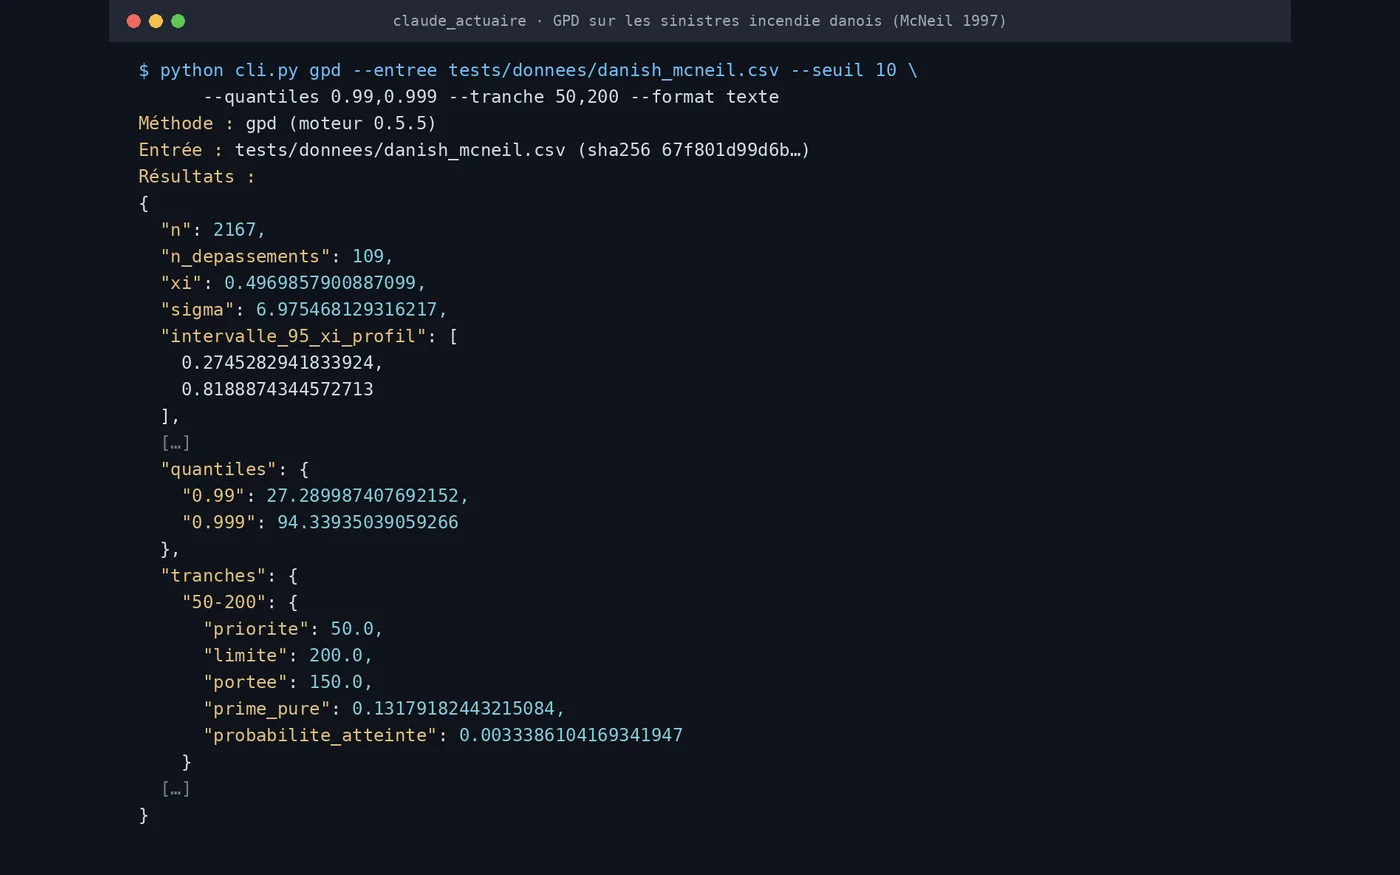
McNeil (1997) reproduced
Backtest
2013-2024

R, targets, testthat, Quarto, Shiny

Platforms and tools

SIAP

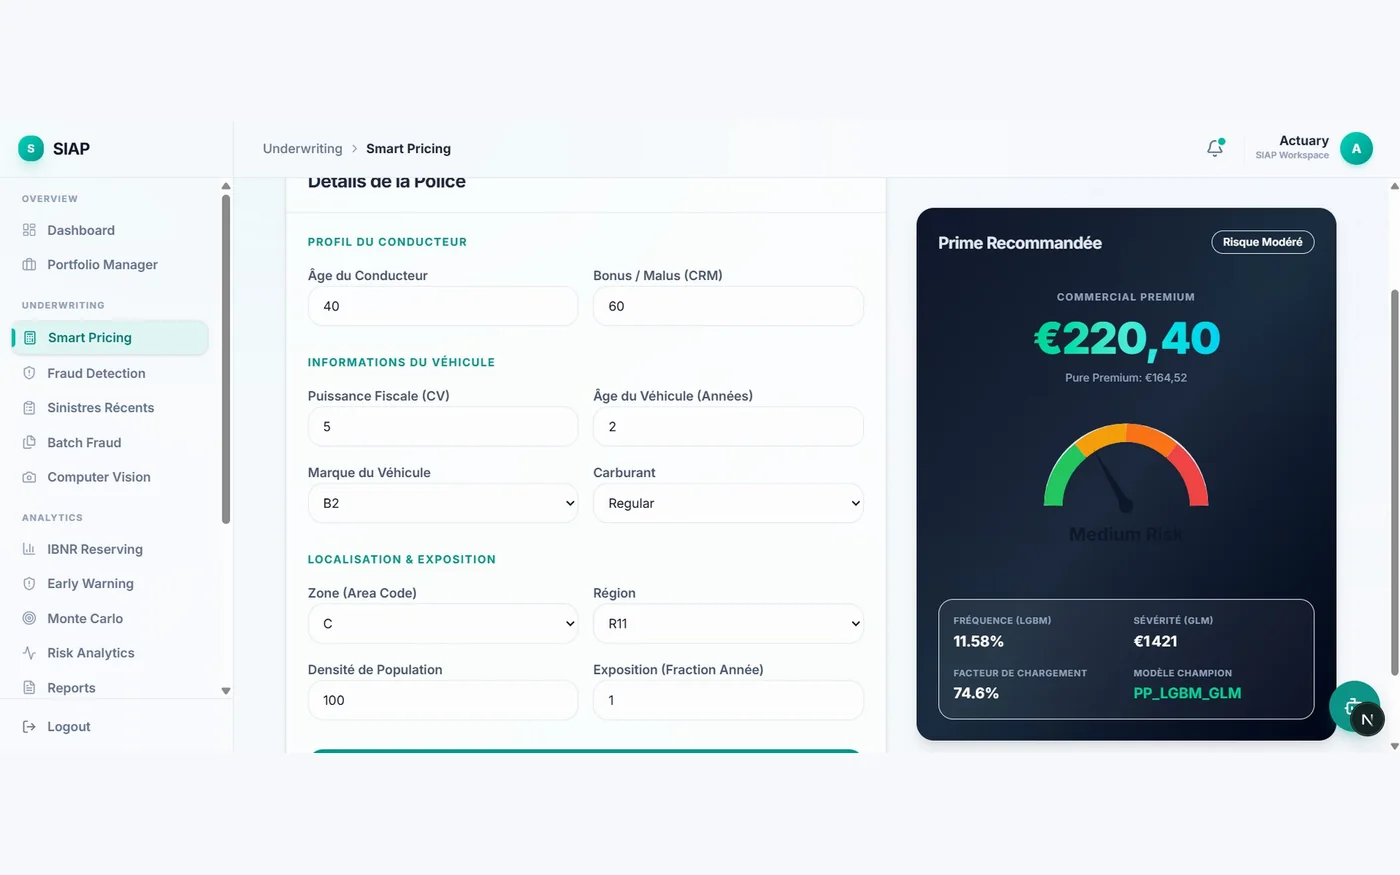
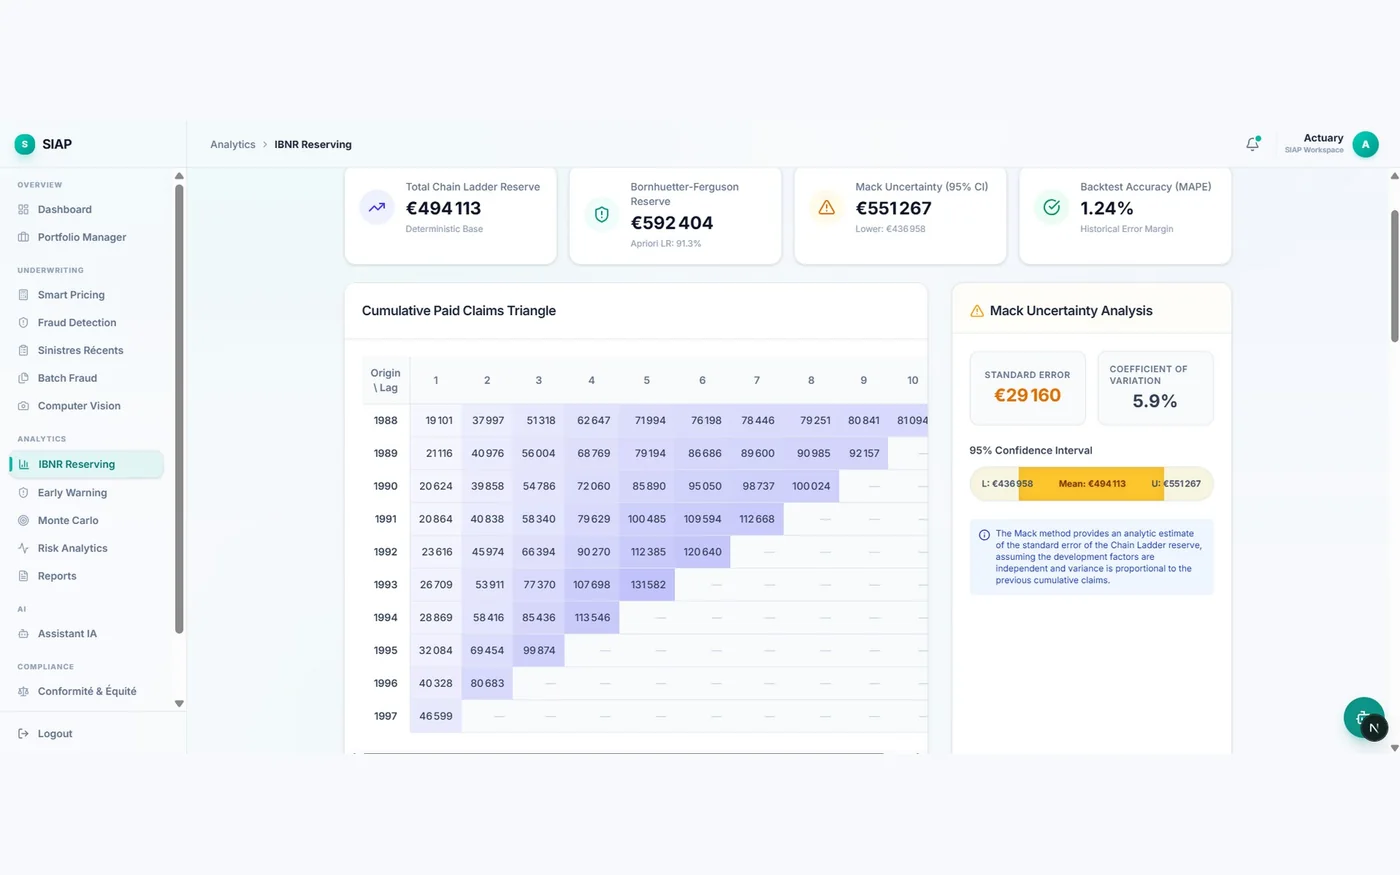
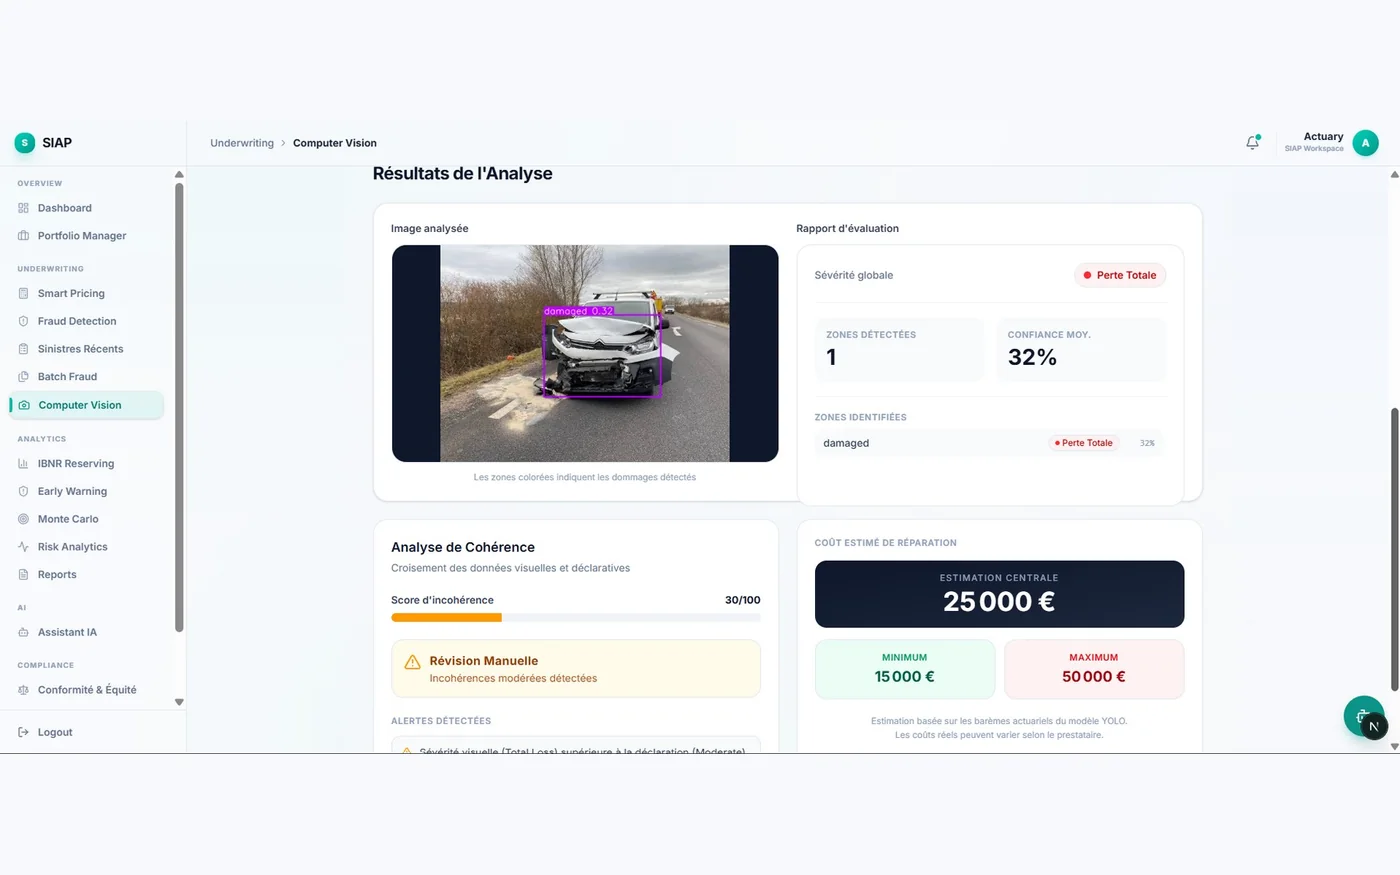
A non-life insurance platform: GLM and LightGBM pricing on 678,000 policies, fraud detection (AUC 0.82), IBNR by Chain Ladder, Mack and bootstrap, and damage assessment by computer vision.

LightGBM, XGBoost, YOLOv8, FastAPI, Next.js

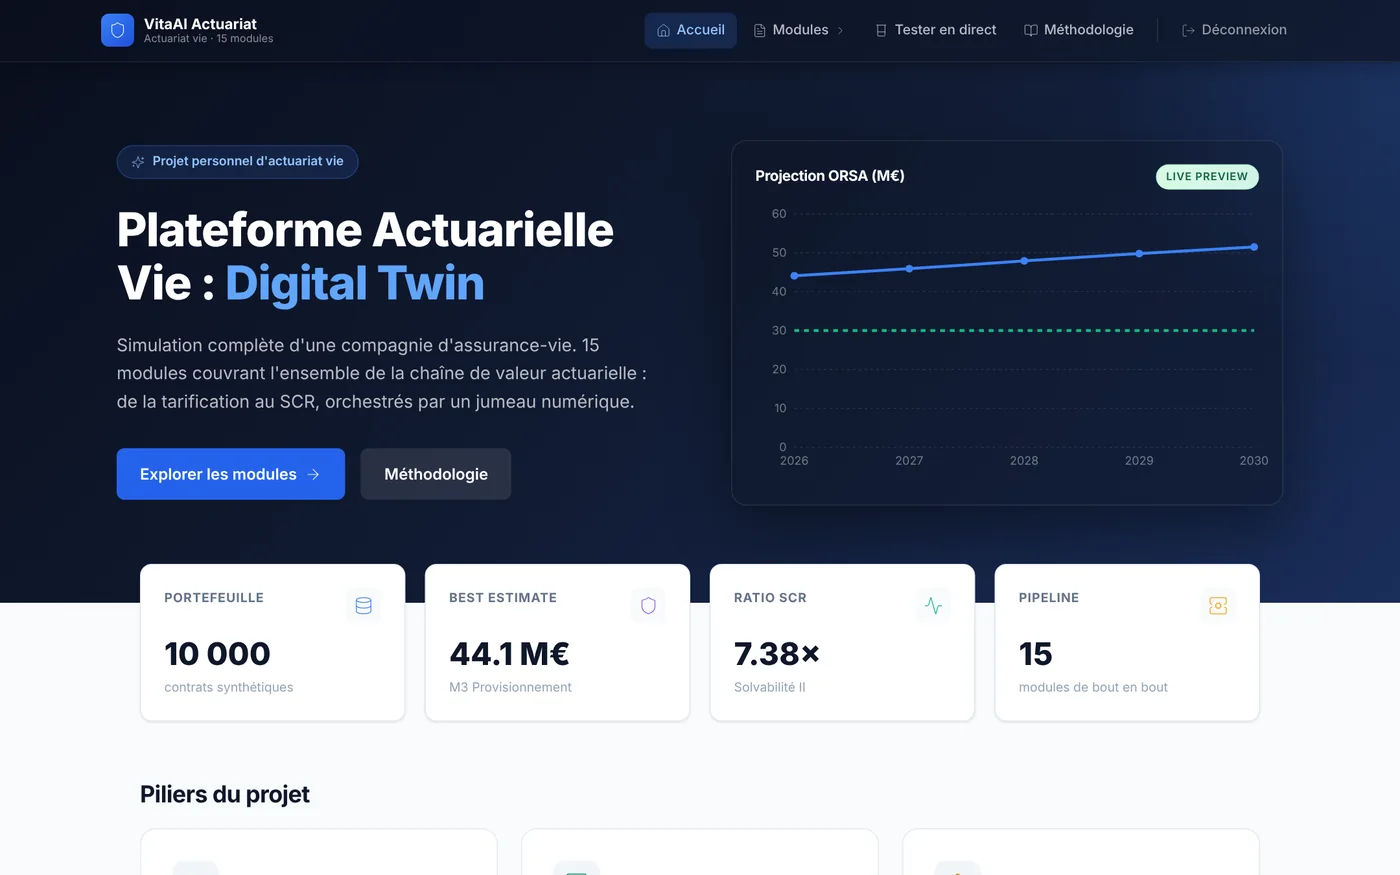
VitaAI

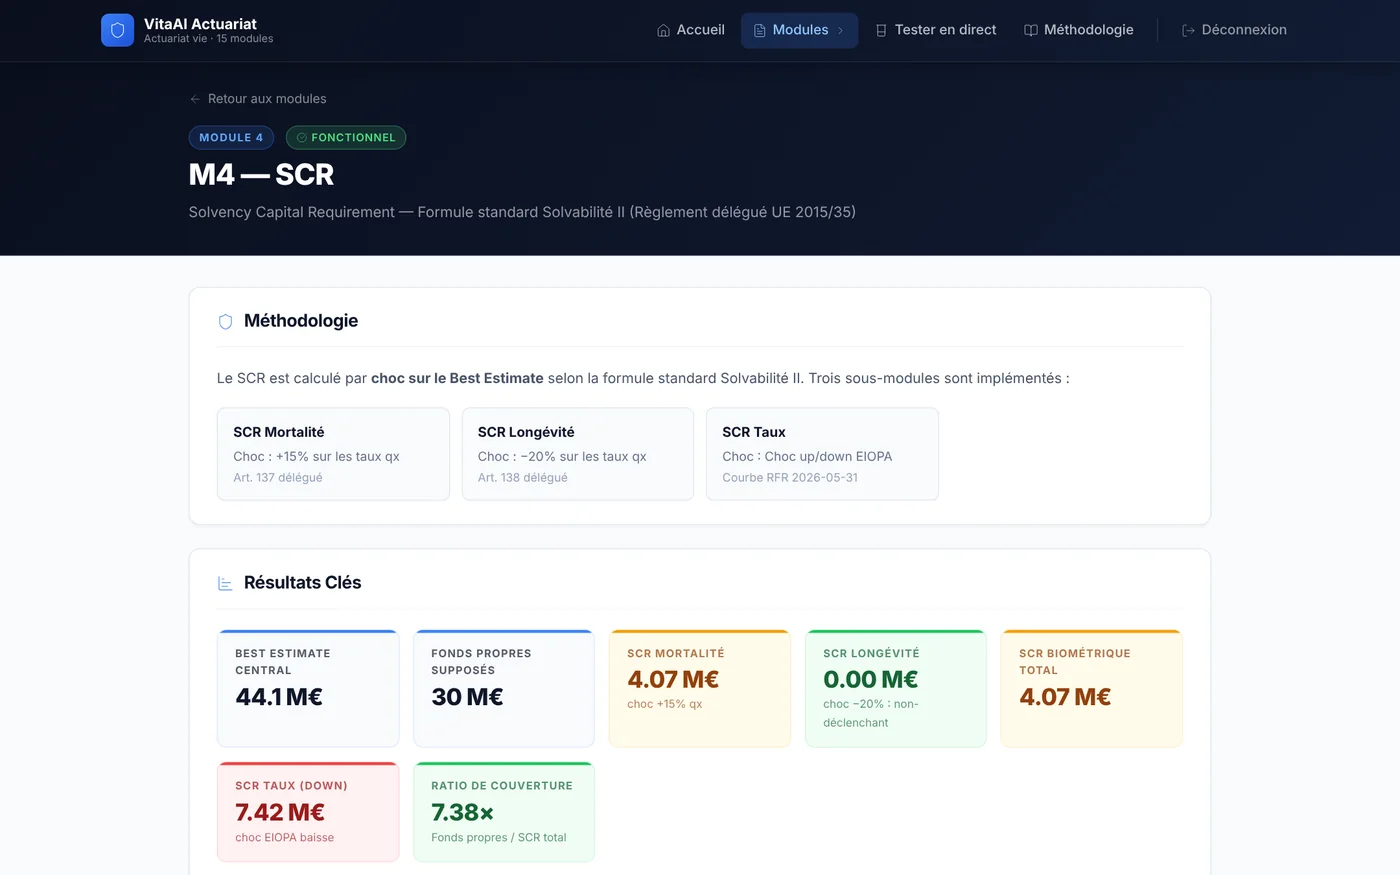
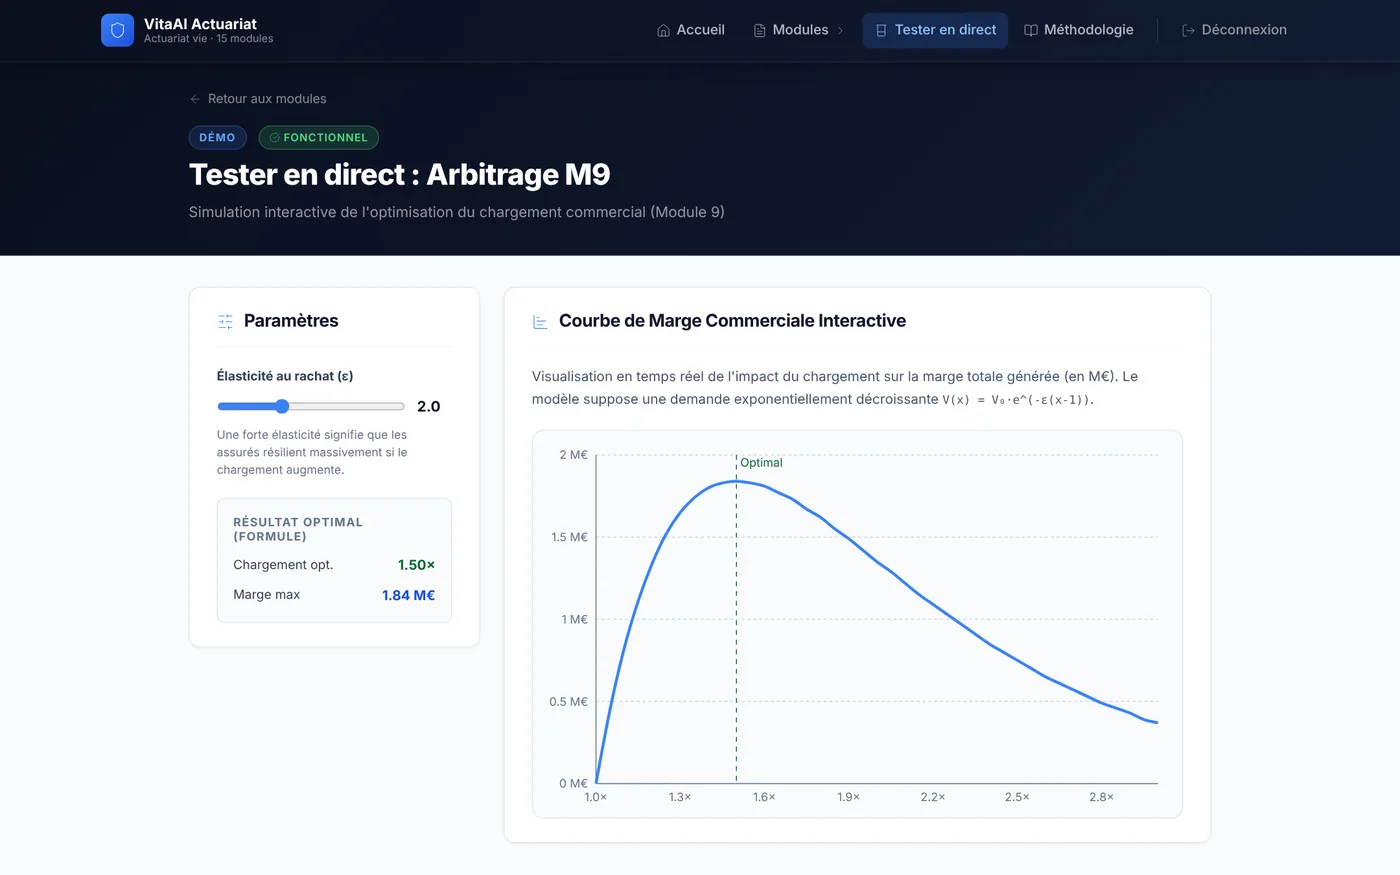
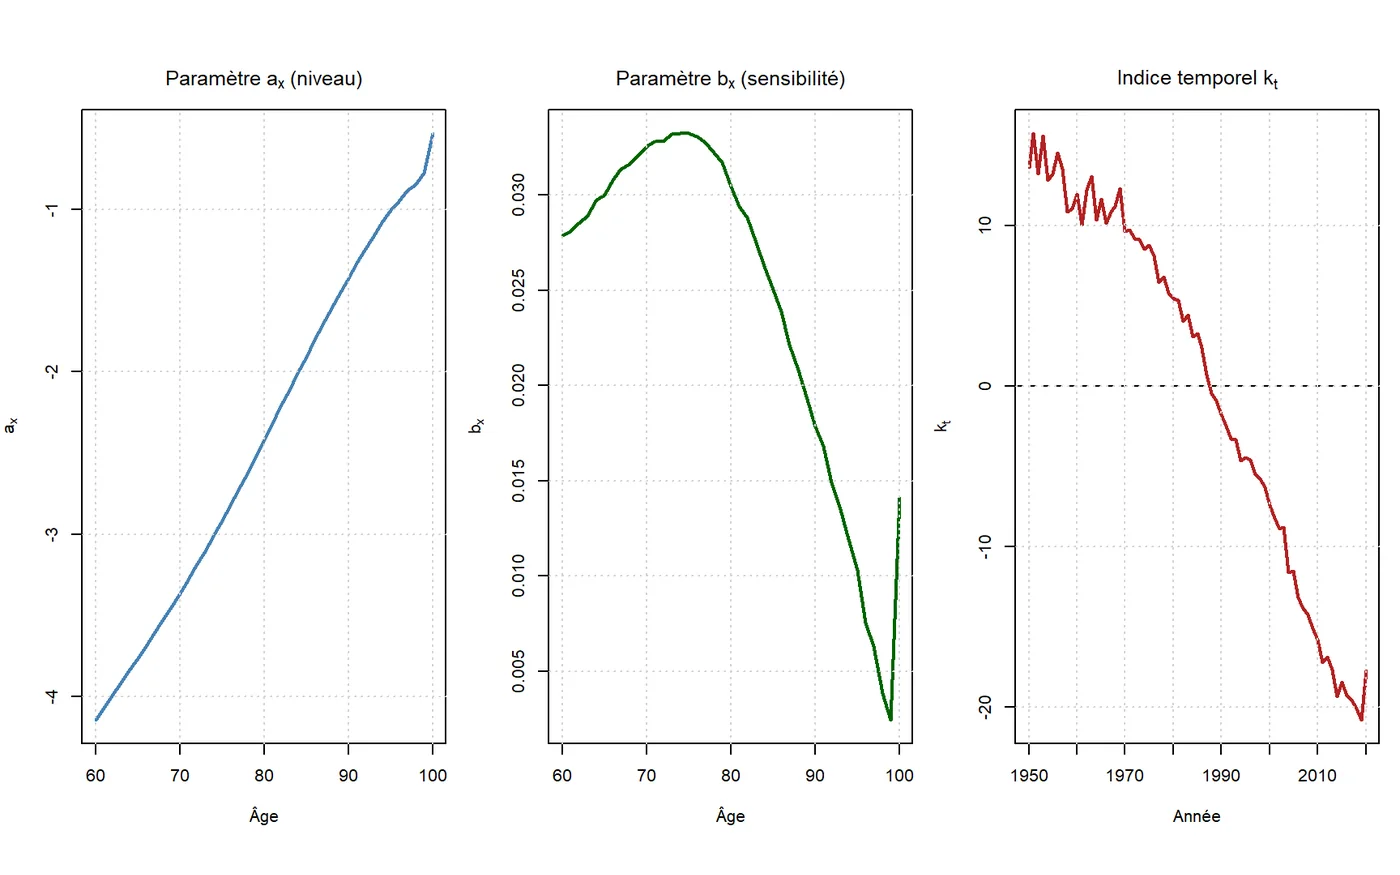
A life insurer simulated in 15 modules: Lee-Carter mortality, reserves, SCR on EIOPA curves, 99.5% longevity VaR, ALM and ORSA.

Python, pytest, Next.js

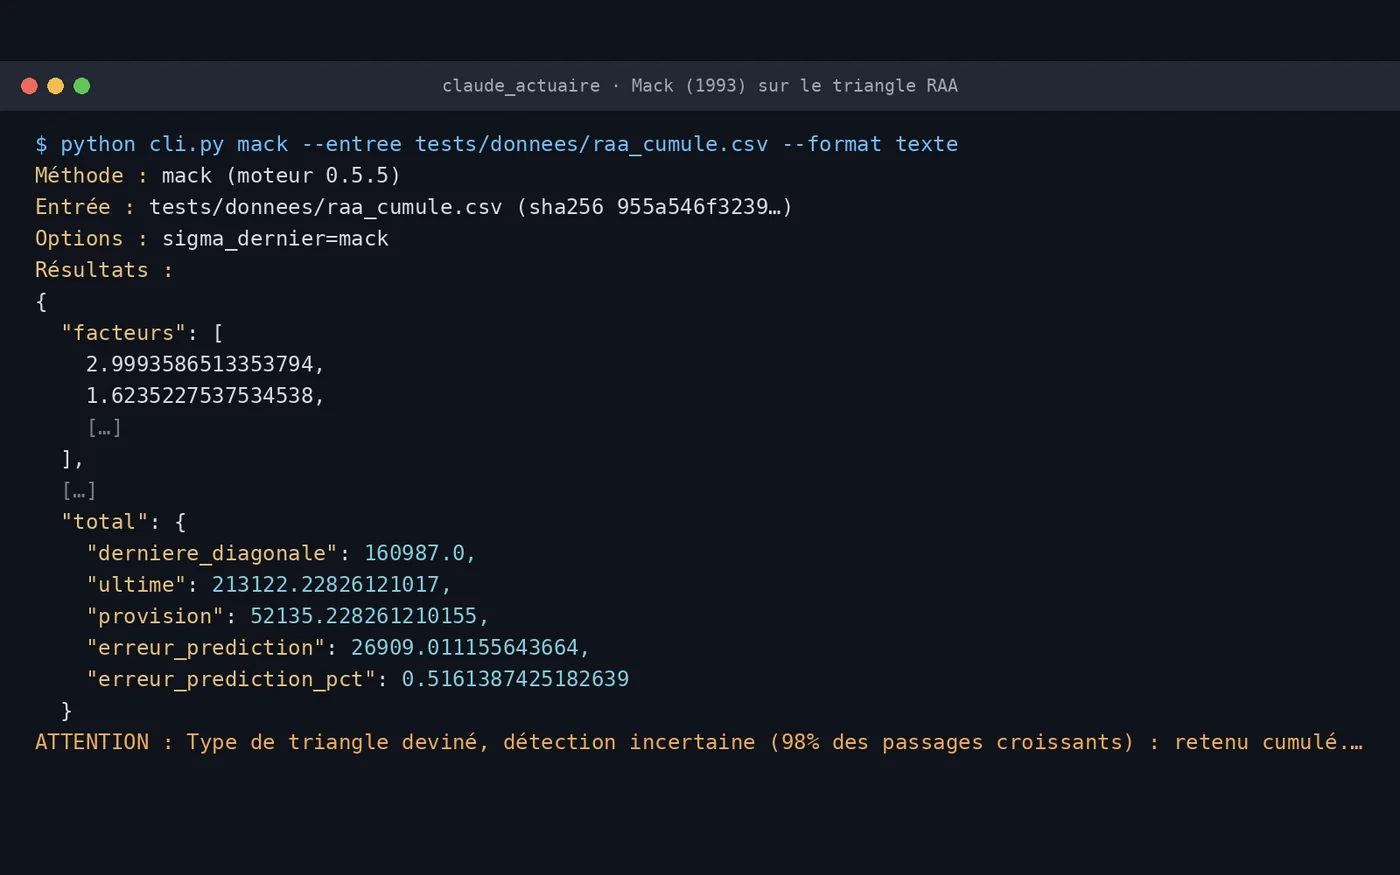
claude_actuaire

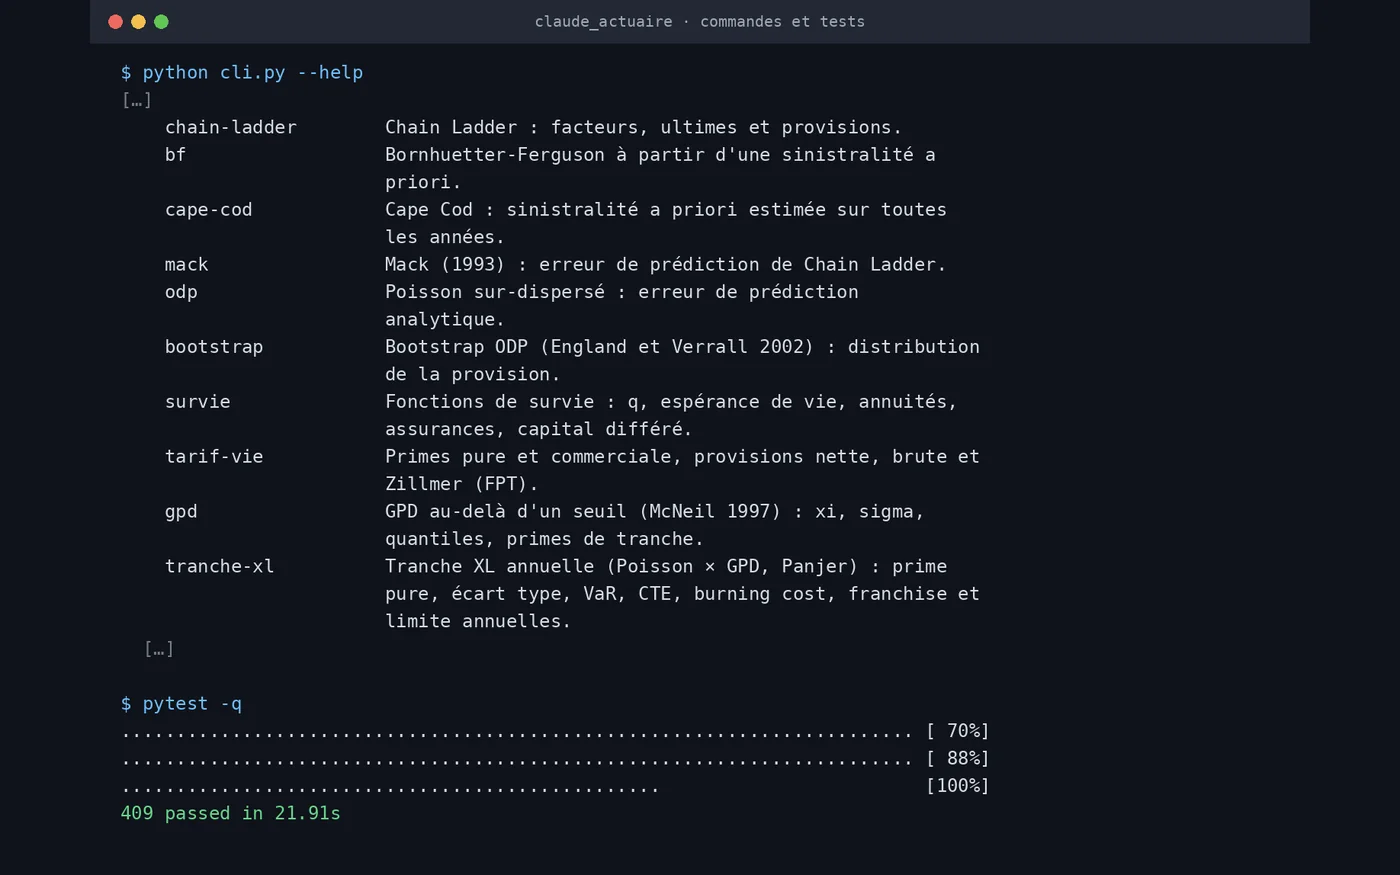
An actuarial calculation engine shipped as a skill for Claude, tested against published results (Mack 1993, McNeil 1997): 59 correct values out of 59 on the benchmark, against 47 without code.

Python, pytest, GitHub Actions

Longevity risk

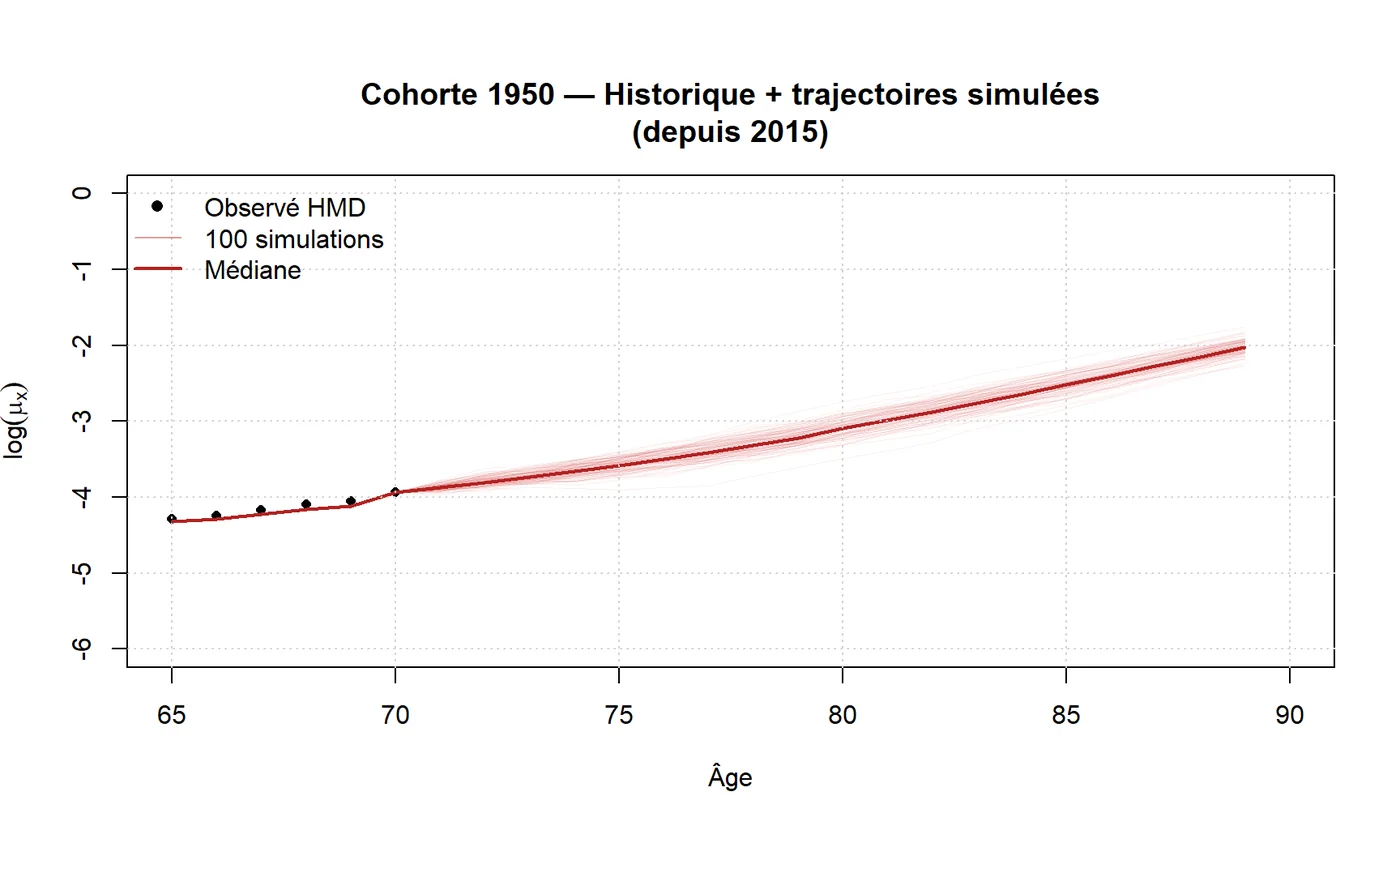
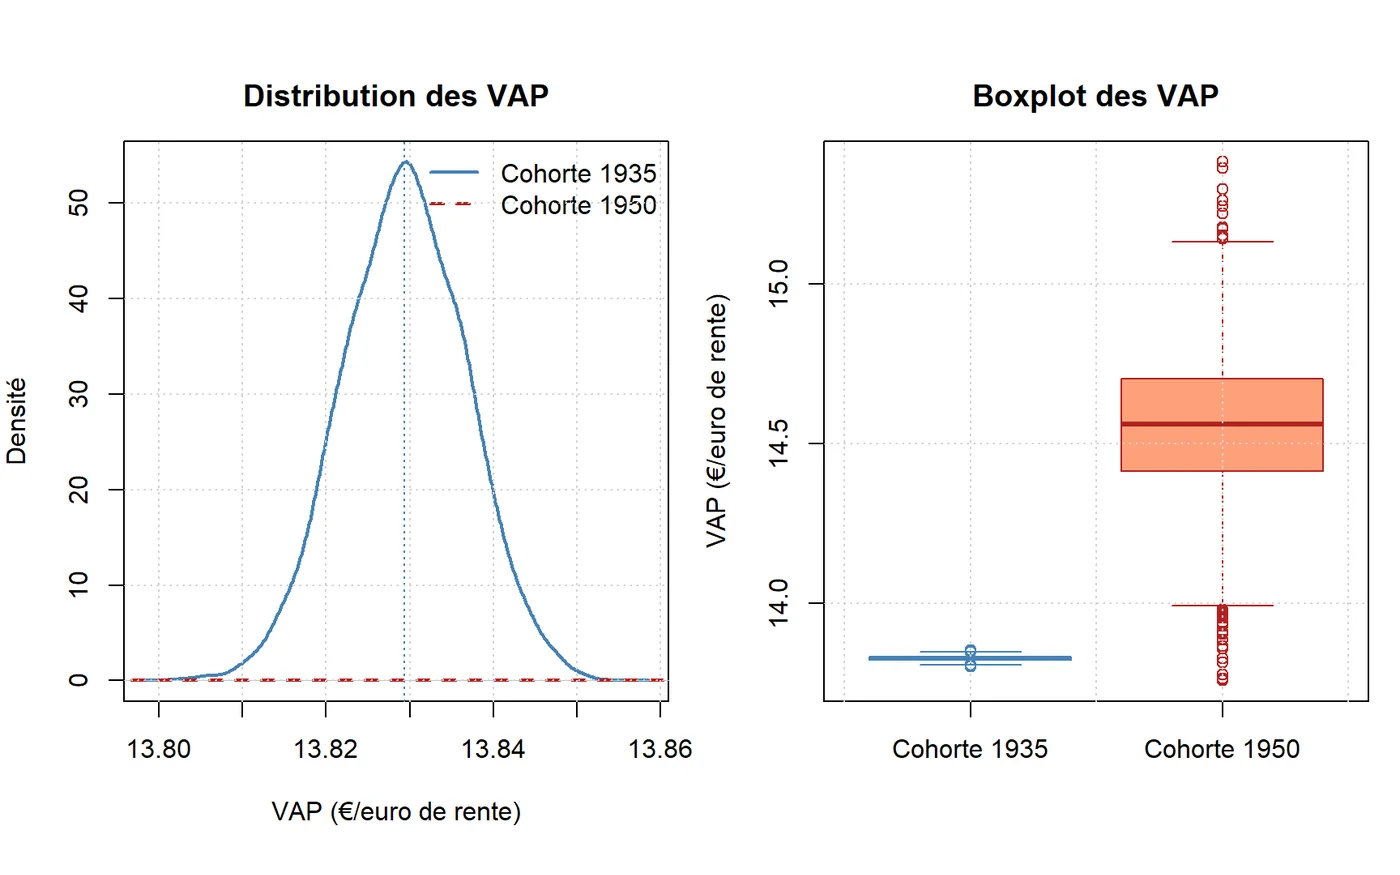
A group project of the MSc Actuarial Science: actuarial present value of a 25-year annuity for two French cohorts. The 1950 generation costs 5.25% more than the 1935 one.

R, StMoMo, R Markdown

QuantAI

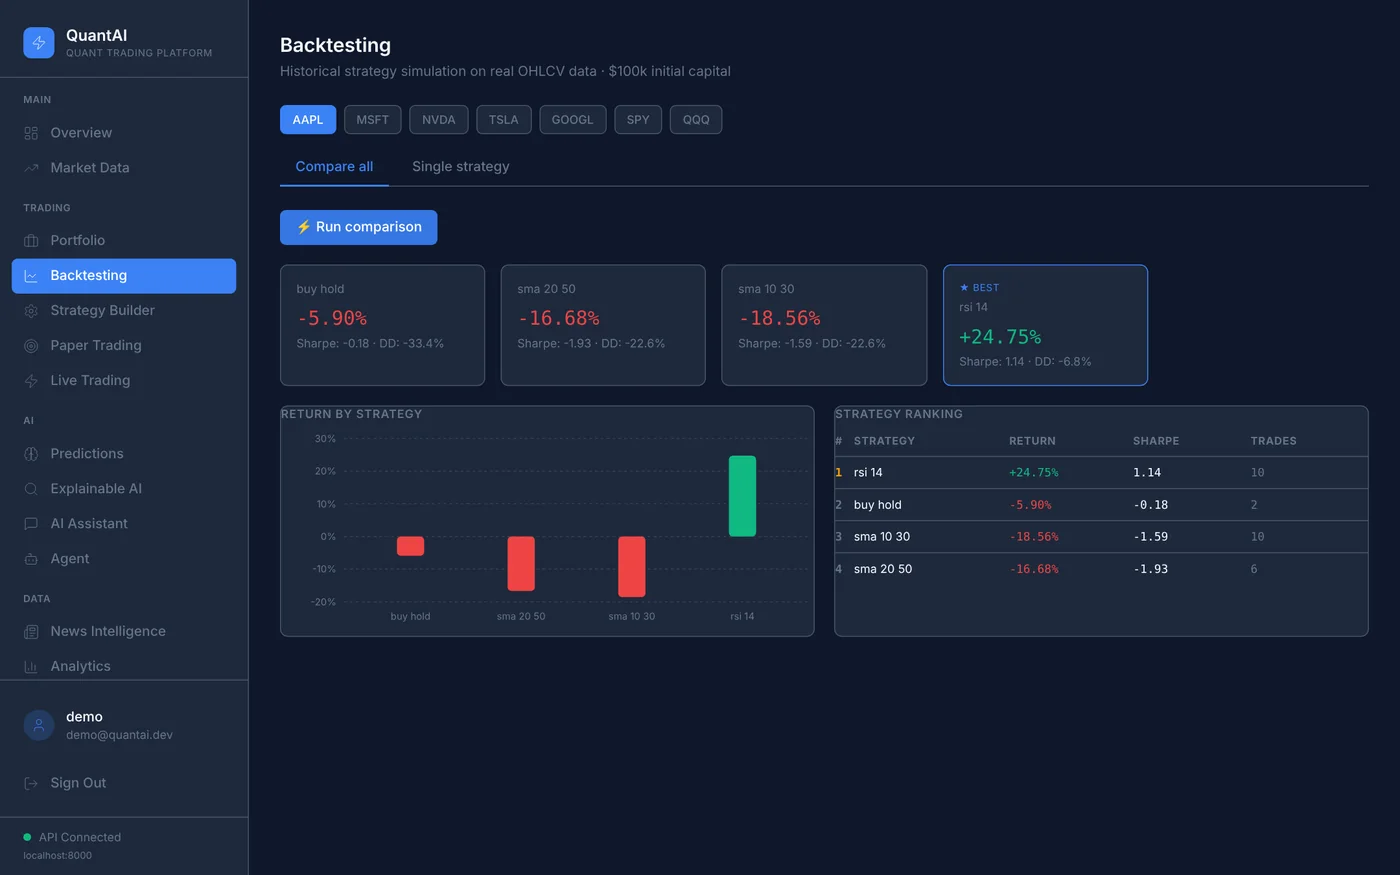
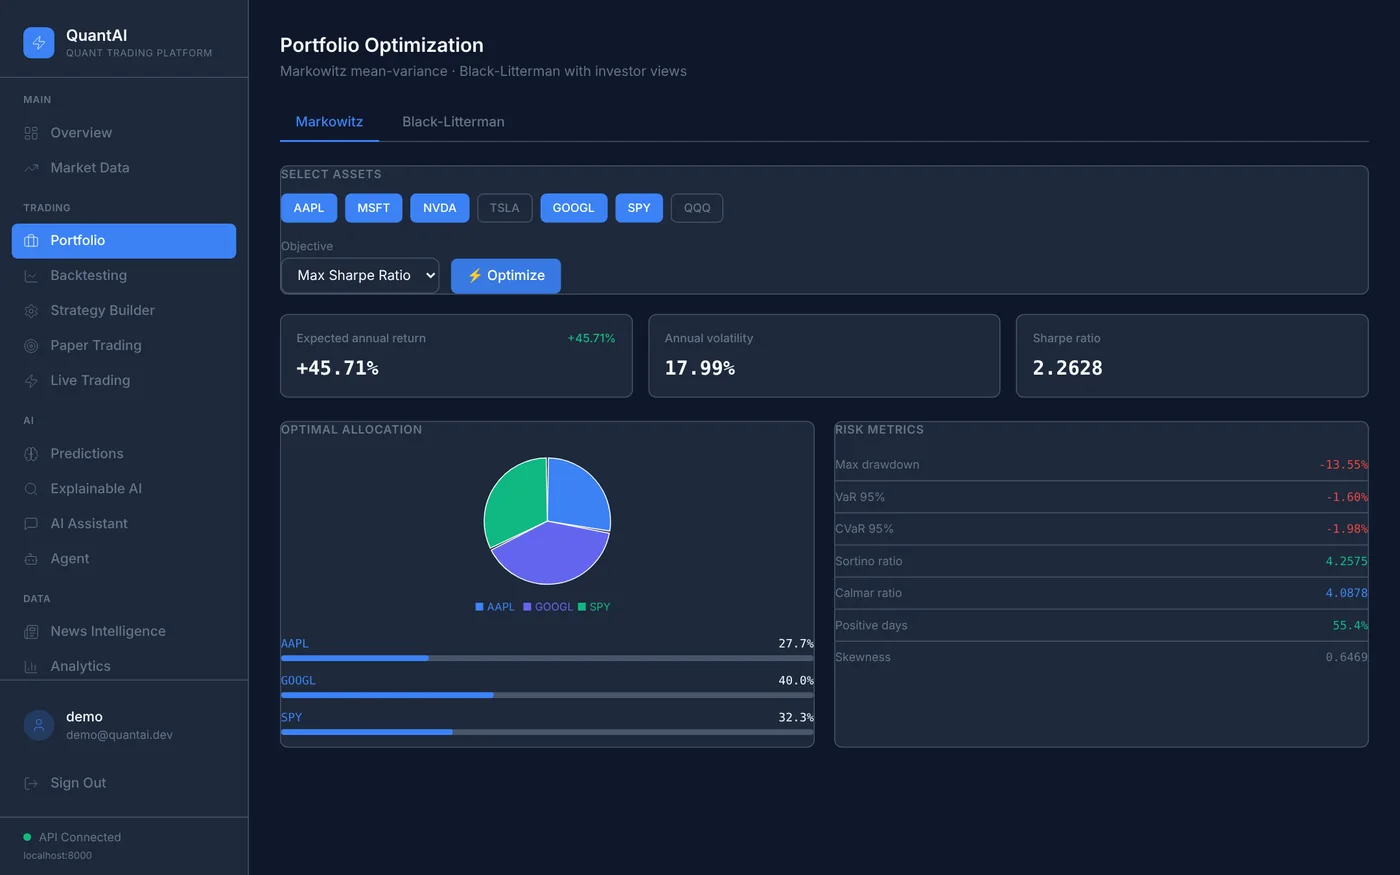
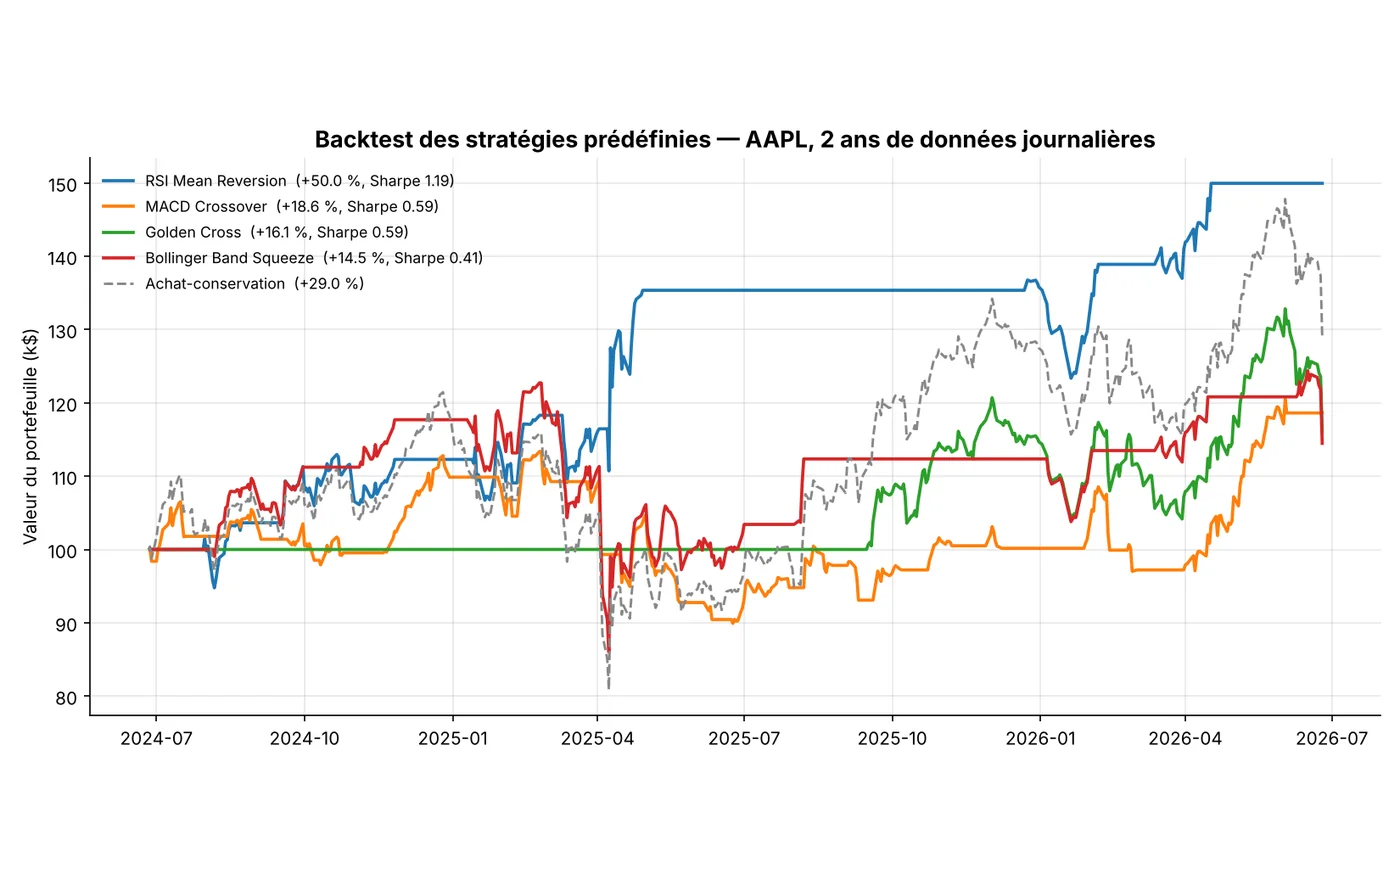
Quantitative trading in paper-trading mode: a LightGBM, LSTM and Transformer ensemble, Markowitz and Black-Litterman optimisation, backtests, and an agent that needs human approval.

PyTorch, FastAPI, Celery, Next.js

Titanic MLOps

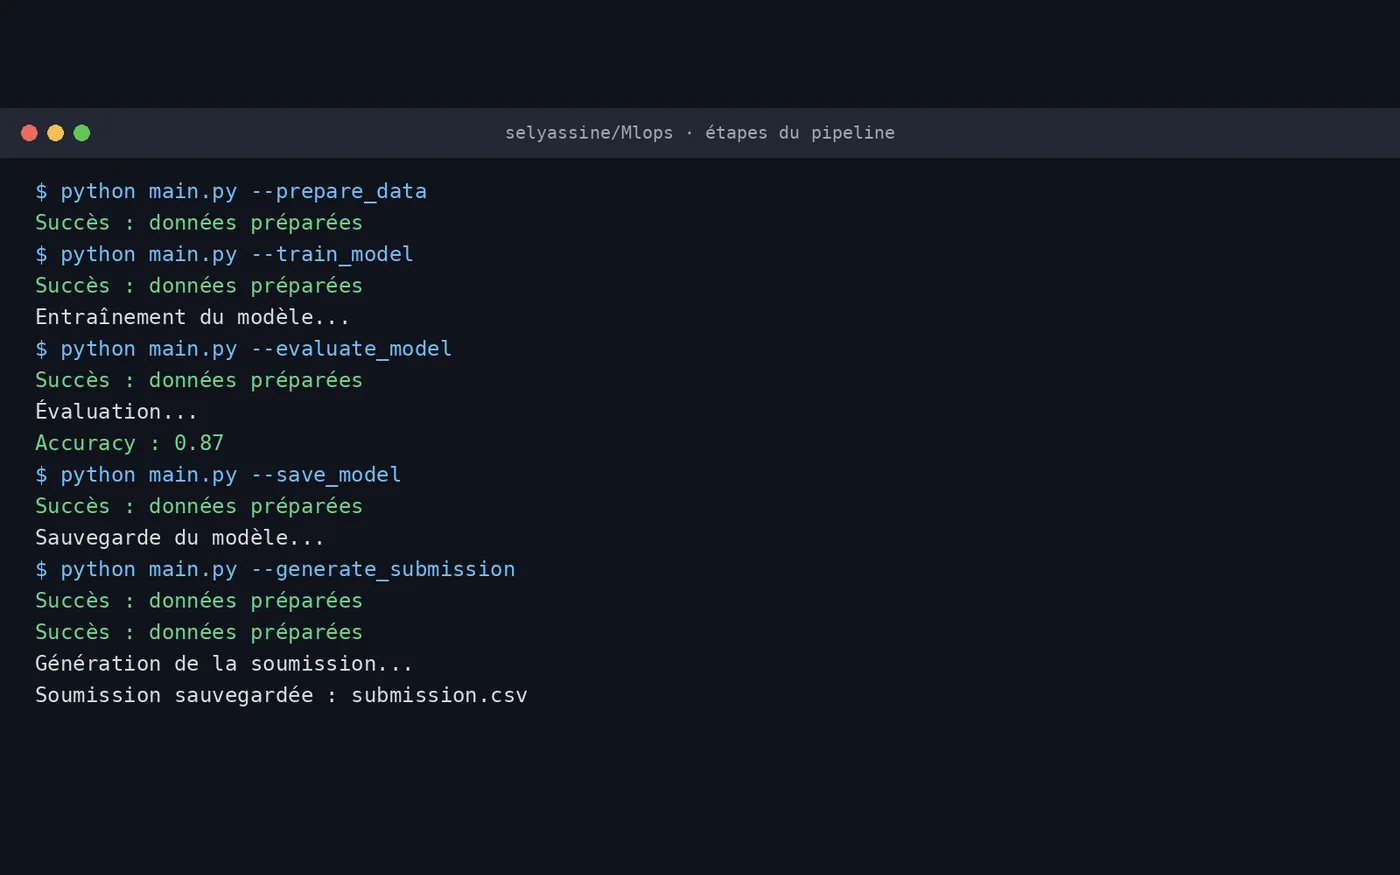
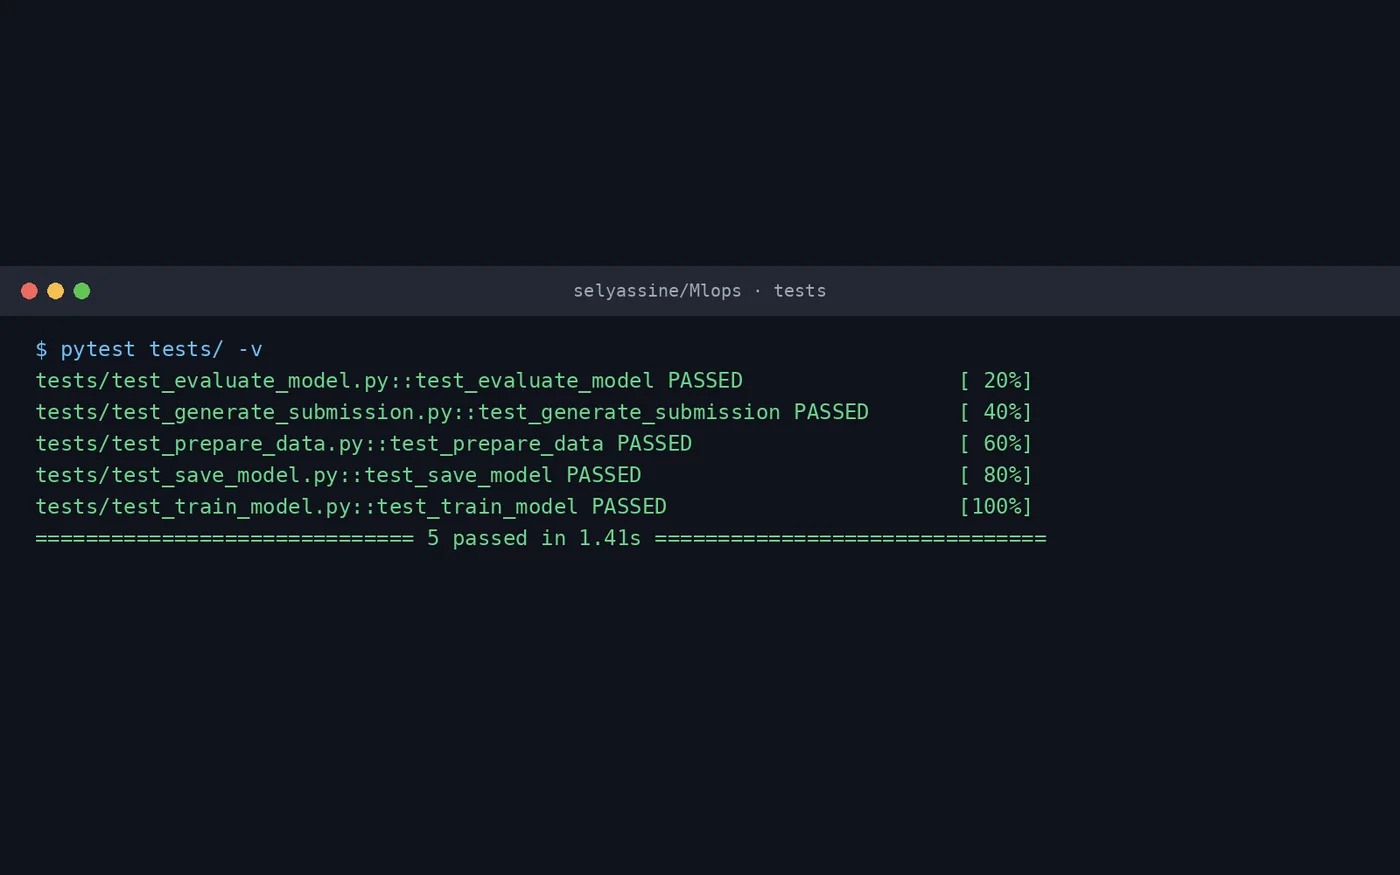
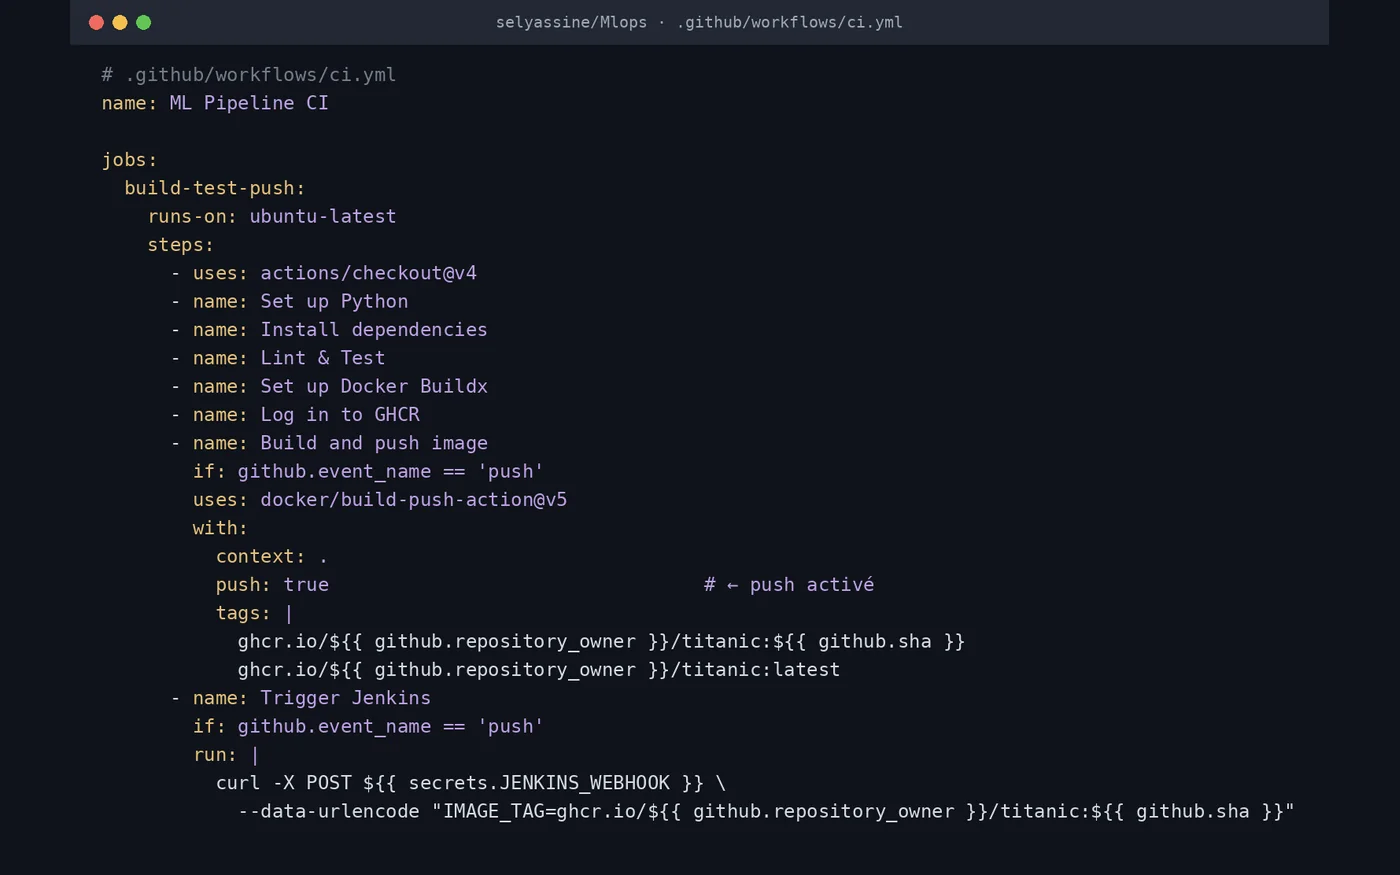
A complete CI/CD pipeline: on every push, the model is tested, containerised, published, then retrained and orchestrated automatically.

Docker, GitHub Actions, Jenkins, Prefect

Other projects
  • BI platform with a conversational agent (2025): Power BI dashboards with role-based security, and a LangChain and Mistral agent that turns questions into SQL.
  • Precision agriculture API: TensorFlow models served by FastAPI to optimise yields.
  • Donation web platform: a React, Node.js and MongoDB application that connects donors and recipients.
  • Social data analysis: indicators extracted with machine learning and reported in Tableau.

Lab

Four actuarial calculations that run inside this page. Change an assumption: the result and the chart are recomputed at once. The formulas are the ones from my projects, on illustrative data.

Complete a claims triangle

Cumulative payments by accident year, in thousands of euros. Edit a white cell: the development factors, the gold cells and the reserve are recomputed.

Reserve (IBNR)
Ultimate cost
Paid to date

The same method, with Mack and the bootstrap, is in SIAP and claude_actuaire.

Method

Three habits found in every repository, which you can check by opening the code.

I validate against a published reference

Before any new calculation, I reproduce a known result: Mack (1993) for reserving, McNeil (1997) for extreme values. Then a second, independent code recomputes the output: 50 IFRS 17 files and 50 IFRS 9 loans redone in R.

I also publish what does not work

In climatXL, the effect of climate on the premium is not demonstrated, and that is the conclusion of the report. In ecl9, both models cover only 9 to 13% of the crisis losses. In IFRS 17 Copilot, an embedding fine-tuning was measured and then dropped.

The language model does not calculate

In my AI tools, every figure comes out of tested code. The model reads the documents, searches the standard, explains and writes. When the data do not allow the calculation, the tool refuses instead of returning a wrong number.

Background

Education and experience, most recent first.

  1. to 2027

    MSc Actuarial Science

    Le Mans Université, double degree with ESPRIT

    Non-life pricing, reserving (Chain Ladder, Bornhuetter-Ferguson), mortality and survival models, Solvency II, IFRS 17, ALM, risk theory and extreme value theory.

  2. Summer

    IFRS 9 credit risk internship

    ESPRIT, RDI department, Tunis

    Estimation of PD, LGD and EAD on portfolio data, and calculation of expected credit losses (ECL) by stage.

  3. Summer , 7 weeks

    Mobile and AI developer internship

    Nour Expert Telecom, Tunis

    A Flutter app for car diagnostics; fault classification with CamemBERT (92% accuracy on 20,000 examples); FastAPI API, Docker, Jenkins CI/CD and Kibana monitoring.

  4. June

    Observation internship

    La Poste Tunisienne, Tunis

    Financial and savings operations, customer data flows, and a first look at risk analysis and control processes.

  5. to 2027

    Engineering degree, data science track

    ESPRIT, Tunis

    Machine learning, deep learning, big data, statistics and intelligent systems.

  6. Baccalaureate in mathematics, with honours

    Tunisia

Skills

What I use in my projects, grouped by field.

Actuarial science
  • IFRS 17: general model, PAA, CSM, risk adjustment
  • Reserving: Chain Ladder, Mack, Bornhuetter-Ferguson, bootstrap
  • IFRS 9: expected credit losses, PD, LGD, EAD
  • Solvency II: SCR, EIOPA curves, ORSA, ALM
  • GLM pricing, Lee-Carter mortality, survival analysis
  • VaR, CVaR, Monte Carlo, extreme values
Data science and AI
  • scikit-learn, LightGBM, XGBoost, SHAP
  • PyTorch, Transformers, NLP, vision (YOLOv8)
  • LLMs, RAG, LangGraph agents, rigorous evaluation
  • Time series, survival analysis
Engineering
  • Python, R, SQL
  • FastAPI, Docker, GitHub Actions, Jenkins
  • n8n, Prefect, MLflow
  • Next.js, React, TypeScript, Power BI
  • Hedera, Solidity smart contracts
Languages
  • Arabic: native
  • French: B2, studies in French
  • English: B2

Certifications

Eleven certifications and certificates earned, one in progress.

Actuarial science and finance

  • Foundations of Insurance and the IFRS 17 StandardSAS
  • AIG Actuarial Analyst Job SimulationForage
  • Credit Risk Modeling in Python365 Financial Analyst

AI and data

  • Building RAG Agents with LLMsNVIDIA DLI
  • Building Transformer-Based NLP ApplicationsNVIDIA DLI
  • Applications of AI for Anomaly DetectionNVIDIA DLI
  • Rapid Application Development with LLMsNVIDIA DLI
  • Building LLM Applications With Prompt EngineeringNVIDIA DLI
  • Data Analyst AssociateDataCampin progress

Blockchain

  • Hedera Certified Developer Associate (HCDA)The Hashgraph Association
  • Hedera Business Foundation (HBF)The Hashgraph Association
  • Hedera Certified Foundation (HCF)The Hashgraph Association

Contact me

I am looking for a 6-month final-year internship starting January 2027, in actuarial science, risk modelling or data science. For an internship, a project or a question about my work, write to me.

City
Tunis, Tunisia

Your mail app opens with the message already filled in, ready to send to selmi.yassine@esprit.tn.